Hidden Costs of Homeownership Add up to $21,466 per Year — Not Including the Mortgage

In expensive states, the typical homeowner could need more than $35,000 annually for recurring costs like insurance, taxes, and maintenance.

Matt Brannon
Writer: Matt BrannonSenior Economic Analyst, Licensed Insurance Agent

Qualifications:
  • 11+ years in content creation

  • 4+ years in business and financial services content

  • NPN: 22276396


Matt is a senior economic analyst and insurance correspondent at Insurify. His work is cited by media outlets nationwide.

Evelyn Pimplaskar
Editor: Evelyn PimplaskarEditor-in-Chief, Director of Content

Qualifications:
  • 10+ years in insurance and personal finance content

  • 30+ years in media, PR, and content creation


Evelyn leads Insurify’s content team. She’s passionate about creating empowering content to help people transform their financial lives and make sound insurance-buying decisions.

Published

Why you can trust Insurify: Comparing accurate insurance quotes should never put you at risk of spam. We earn an agent commission only if you buy a policy based on our quotes. Our editorial team follows a rigorous set of editorial standards and operates independently from our insurance partners. Learn more.

Home insurance and maintenance costs have risen rapidly since 2020. Now, even those who can comfortably afford their mortgages are seeing hidden homeownership costs strain their budgets.

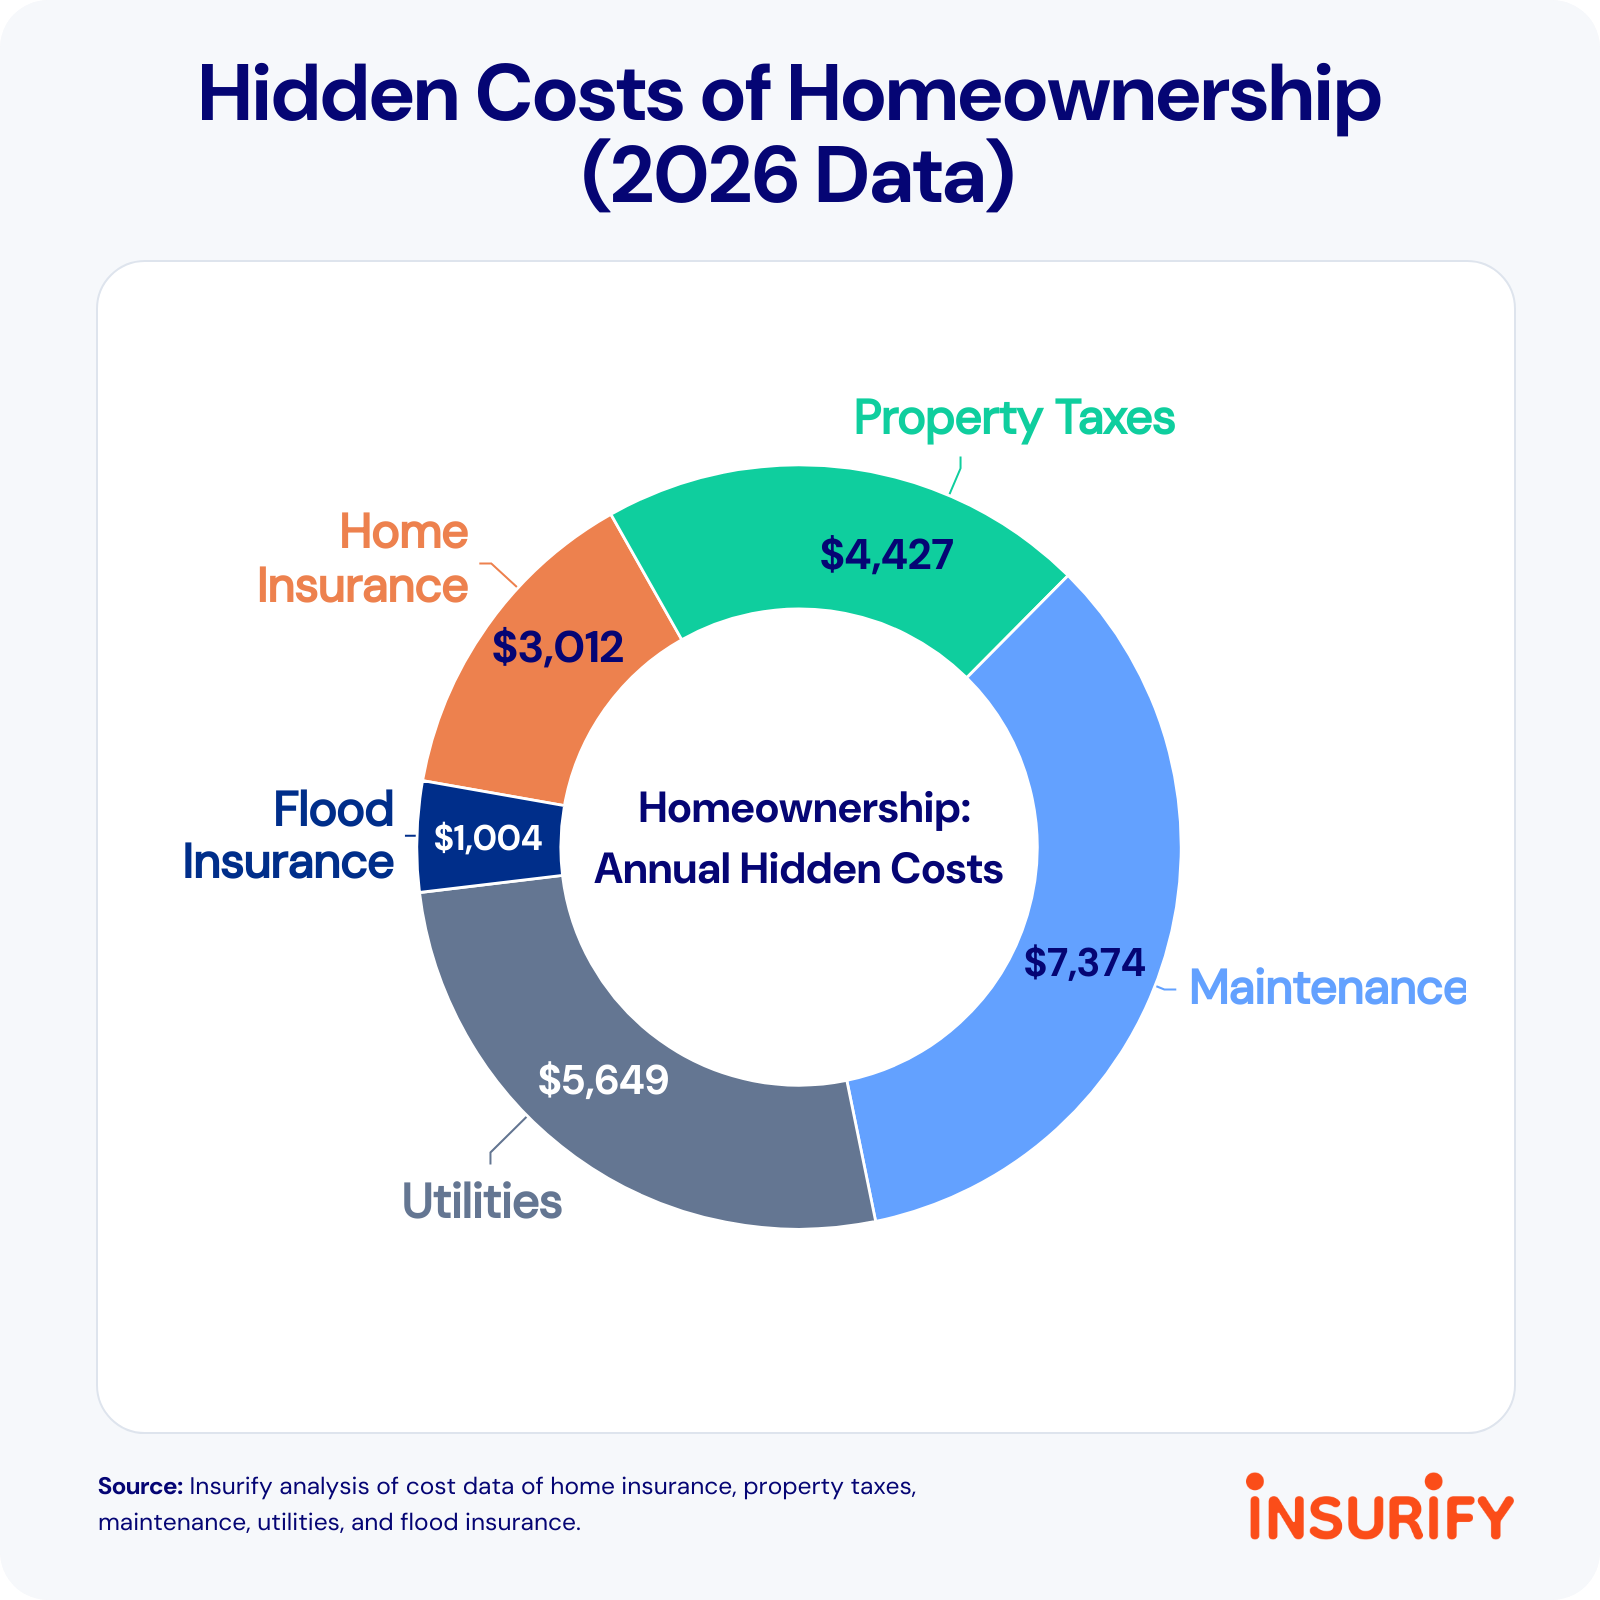
The hidden costs of homeownership now total $21,466, not including mortgage principal and interest. That total encompasses five recurring expenses that homeowners often underestimate:

Hidden Cost
Average Annual Cost
Maintenance$7,374
Utilities$5,649
Property taxes$4,427
Home insurance$3,012
Flood insurance$1,004

Flood insurance has risen the sharpest in the past year, with the average annual cost jumping 9% for National Flood Insurance Program (NFIP) policies, which make up the vast majority of U.S. flood policies.[1] The increase comes as the El Niño weather pattern could lead to severe flooding in 2026, meteorologists warn.[2]

Overall, the Consumer Price Index for housing is up 34% since 2020.[3] Lately, interest rates are putting added pressure on newer homeowners. The average mortgage rate surpassed 7% in September, marking a three-year high.[4]

As a result, newer homeowners are paying more on their mortgages. A house that would have had a monthly mortgage payment of $1,400 at 3% interest would now cost $2,200 per month at 7%.

New homebuyers may also have to pay for private mortgage insurance (PMI) until they reach 20% equity. PMI could cost about $1,991 per year on average, according to Insurify analysis of Freddie Mac estimates.[5] Membership in a typical homeowners association (HOA) could add another $1,620 annually.[6]

Key findings

  • On top of mortgage principal and interest, owning a home costs about $21,466 per year nationally, and beyond $30,000 in five states.

  • Non-mortgage costs of homeownership are up 2% since 2025. Flood insurance is the fastest-growing homeownership cost since 2025, rising 9% to $1,004.

  • California has the most expensive hidden homeownership costs, totaling $35,527. California homeowners have had utility costs increase 16% and home insurance costs increase 8% since last year.

  • Homeownership costs have risen the fastest in South Carolina, Minnesota, and West Virginia, each seeing about a 9% increase since 2025. In 12 states, hidden costs rose at least $1,000 in the past year.

Hidden costs — and where they’re rising fastest in 2026

Owning a home takes a bigger budget than it used to. Home and flood insurance costs climbed sharply in recent years, in part due to increasingly severe weather. Higher construction material and labor costs make maintenance, renovations, and repairs more expensive. And electricity prices have outpaced inflation since 2022.[7]

In five states, hidden homeownership costs total more than $30,000 annually. Given the financial obstacles, it’s no surprise that 24% of Gen Z believes they’ll never afford a home. In the short term, not buying a house has become a reasonable choice. Compared to homeowners, renters spend thousands less annually on utilities and property insurance and don’t pay directly for maintenance or property taxes.

The Hidden Cost of Homeownership by State (2026)

State
Non-Mortgage Costs, Total
Home Insurance
Property Taxes
Maintenance
Utilities
Flood Insurance
$21,466$3,012$4,427$7,374$5,649$1,004
Alabama$15,868$3,939$1,284$4,832$4,857$956
Alaska$20,916$1,446$4,232$7,973$6,830$435
Arizona$19,094$2,143$2,408$8,360$5,298$885
Arkansas$14,445$3,142$1,387$4,545$4,288$1,083
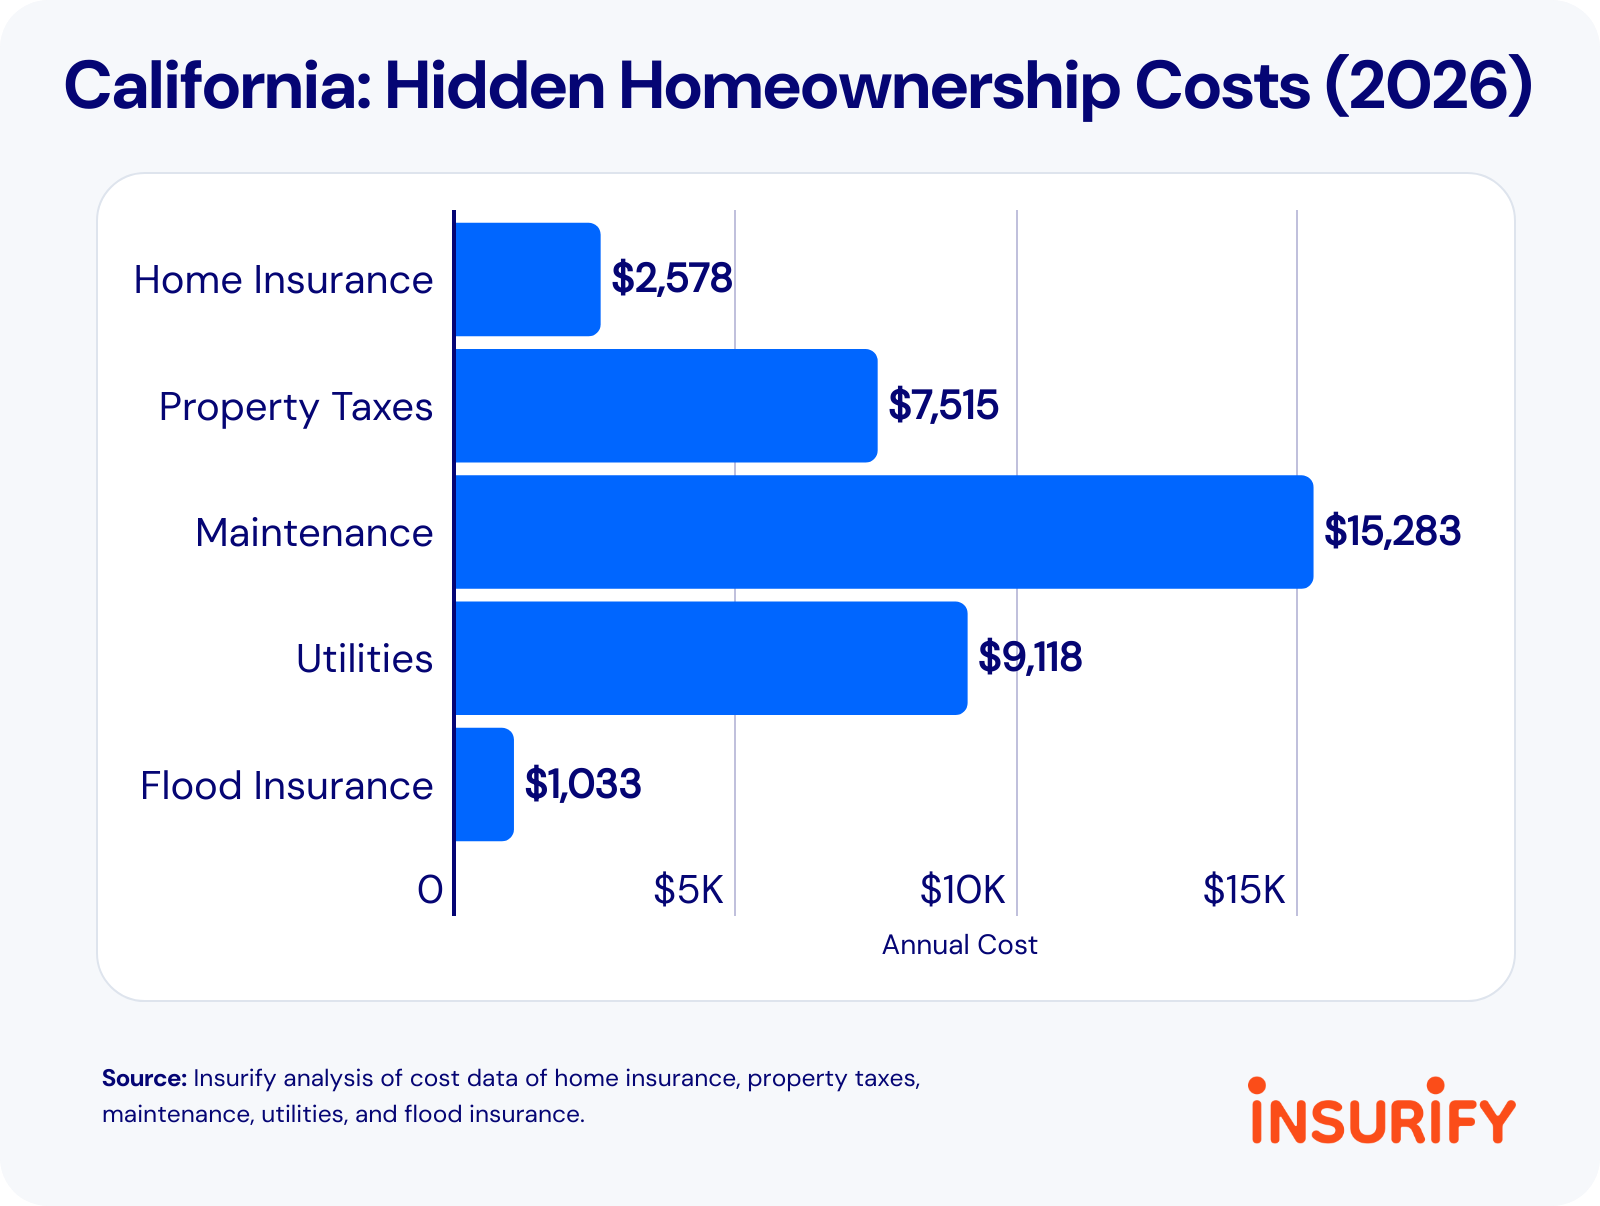
California$35,527$2,578$7,515$15,283$9,118$1,033
Colorado$24,561$4,137$3,892$10,655$4,876$1,001
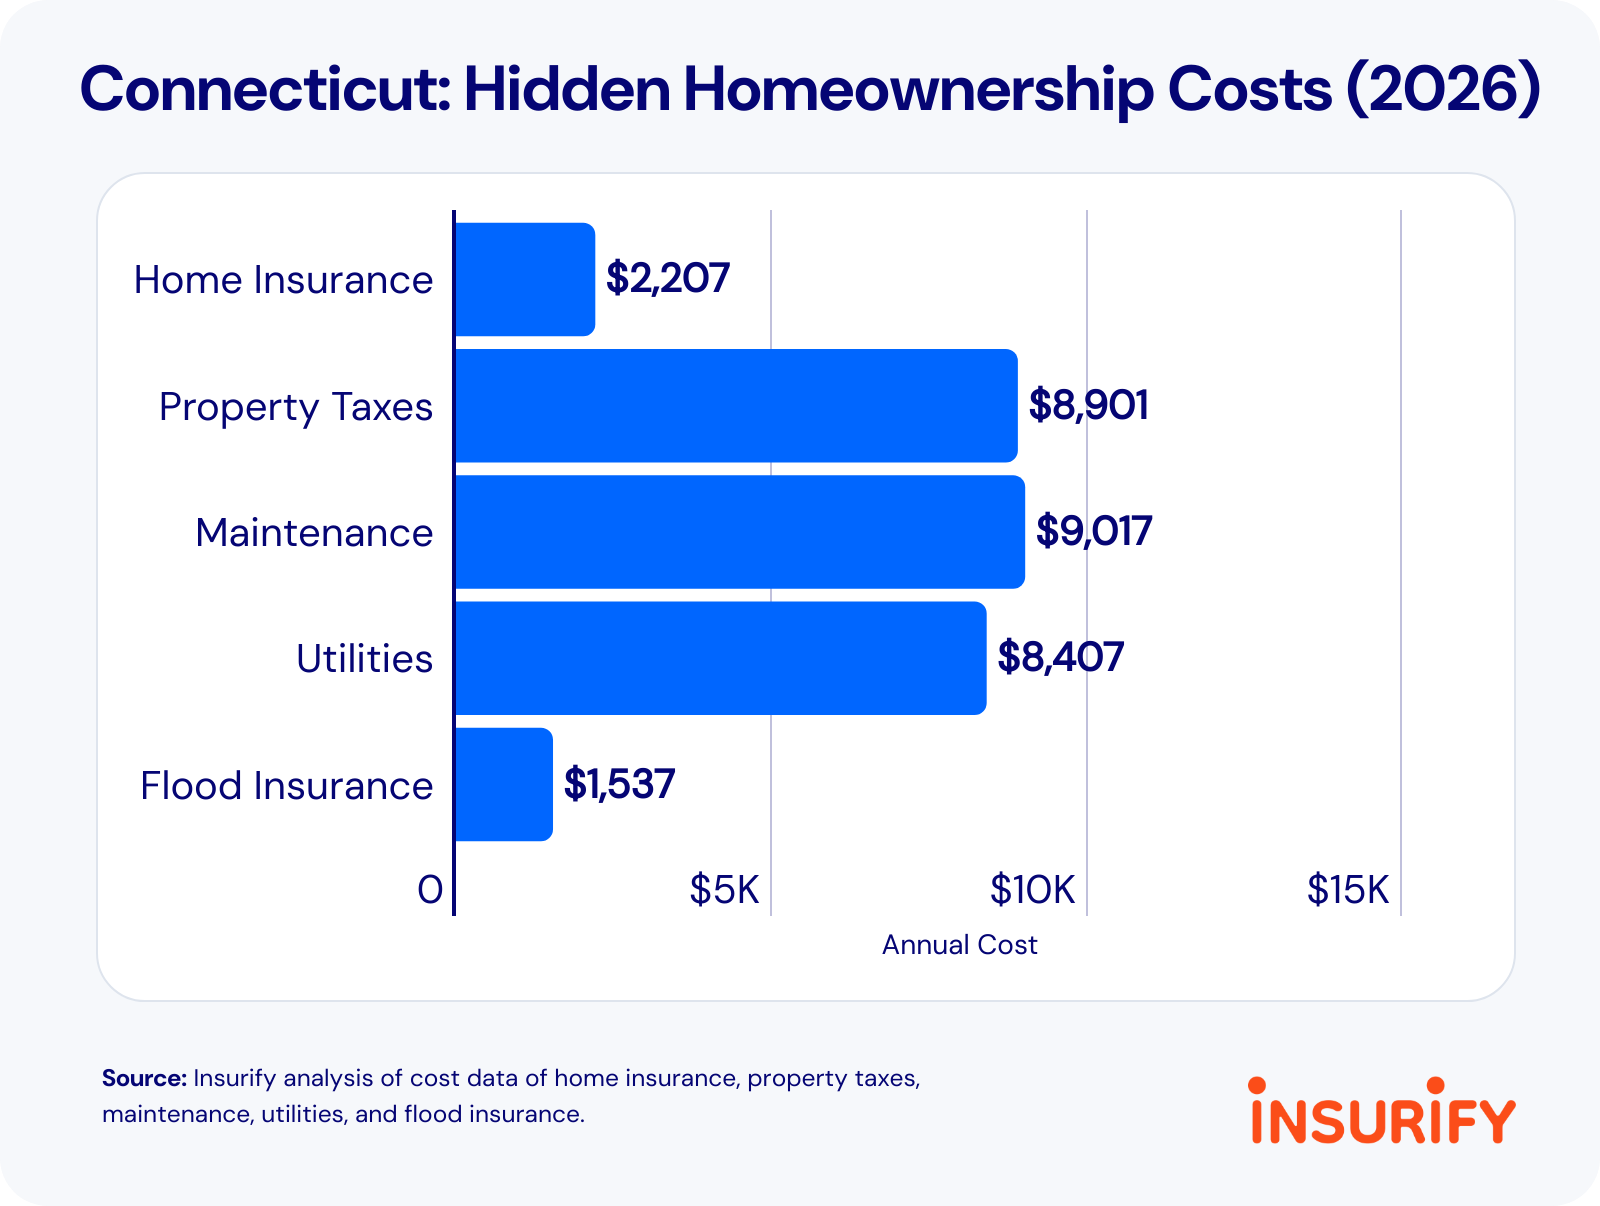
Connecticut$30,069$2,207$8,901$9,017$8,407$1,537
Delaware$18,792$1,403$2,462$8,121$5,957$849
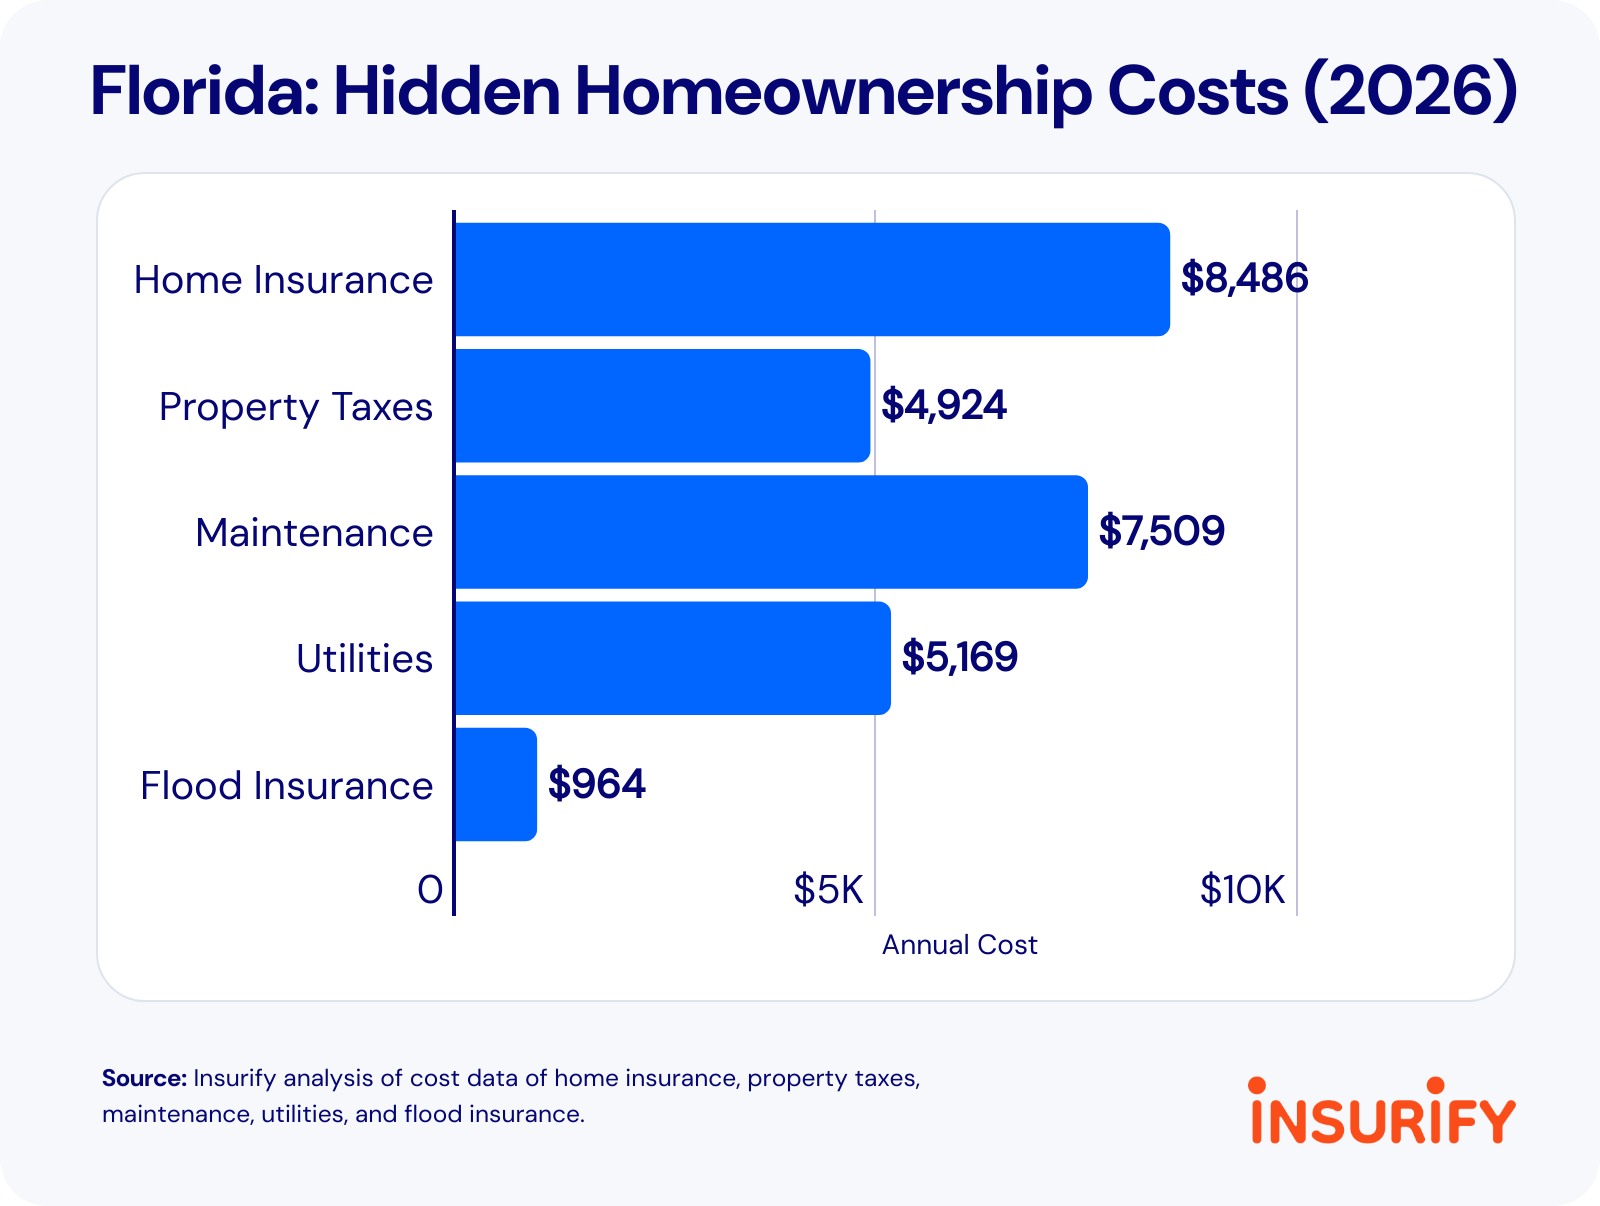
Florida$27,052$8,486$4,924$7,509$5,169$964
Georgia$18,927$2,896$3,174$6,616$5,326$915
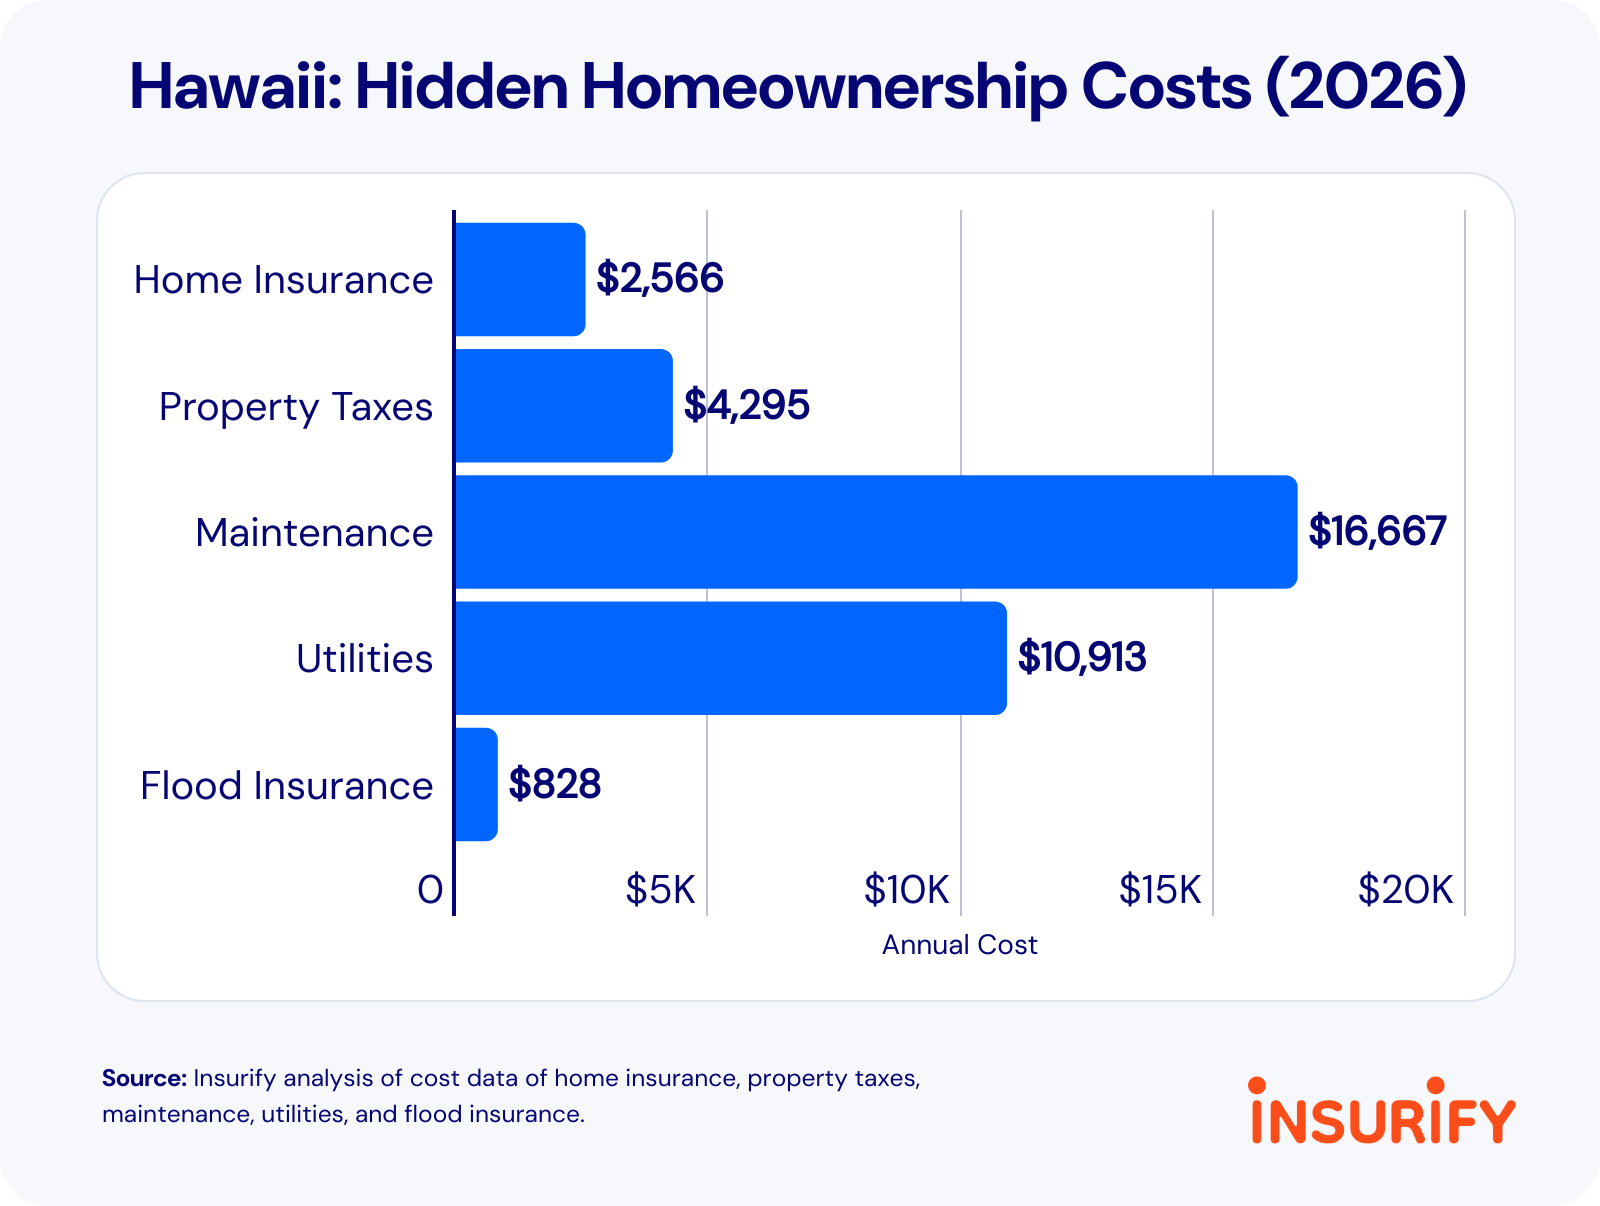
Hawaii$35,269$2,566$4,295$16,667$10,913$828
Idaho$18,658$1,675$2,335$9,575$4,042$1,031
Illinois$21,589$3,414$6,277$5,951$4,875$1,072
Indiana$15,571$1,940$2,482$5,202$4,909$1,038
Iowa$17,058$2,828$3,295$4,791$4,779$1,365
Kansas$18,025$3,301$3,576$4,992$5,075$1,081
Kentucky$15,086$2,820$1,778$4,652$4,322$1,514
Louisiana$16,617$5,484$1,639$4,341$4,101$1,052
Maine$23,357$1,372$4,518$8,311$7,758$1,398
Maryland$22,853$2,209$5,205$8,566$6,362$511
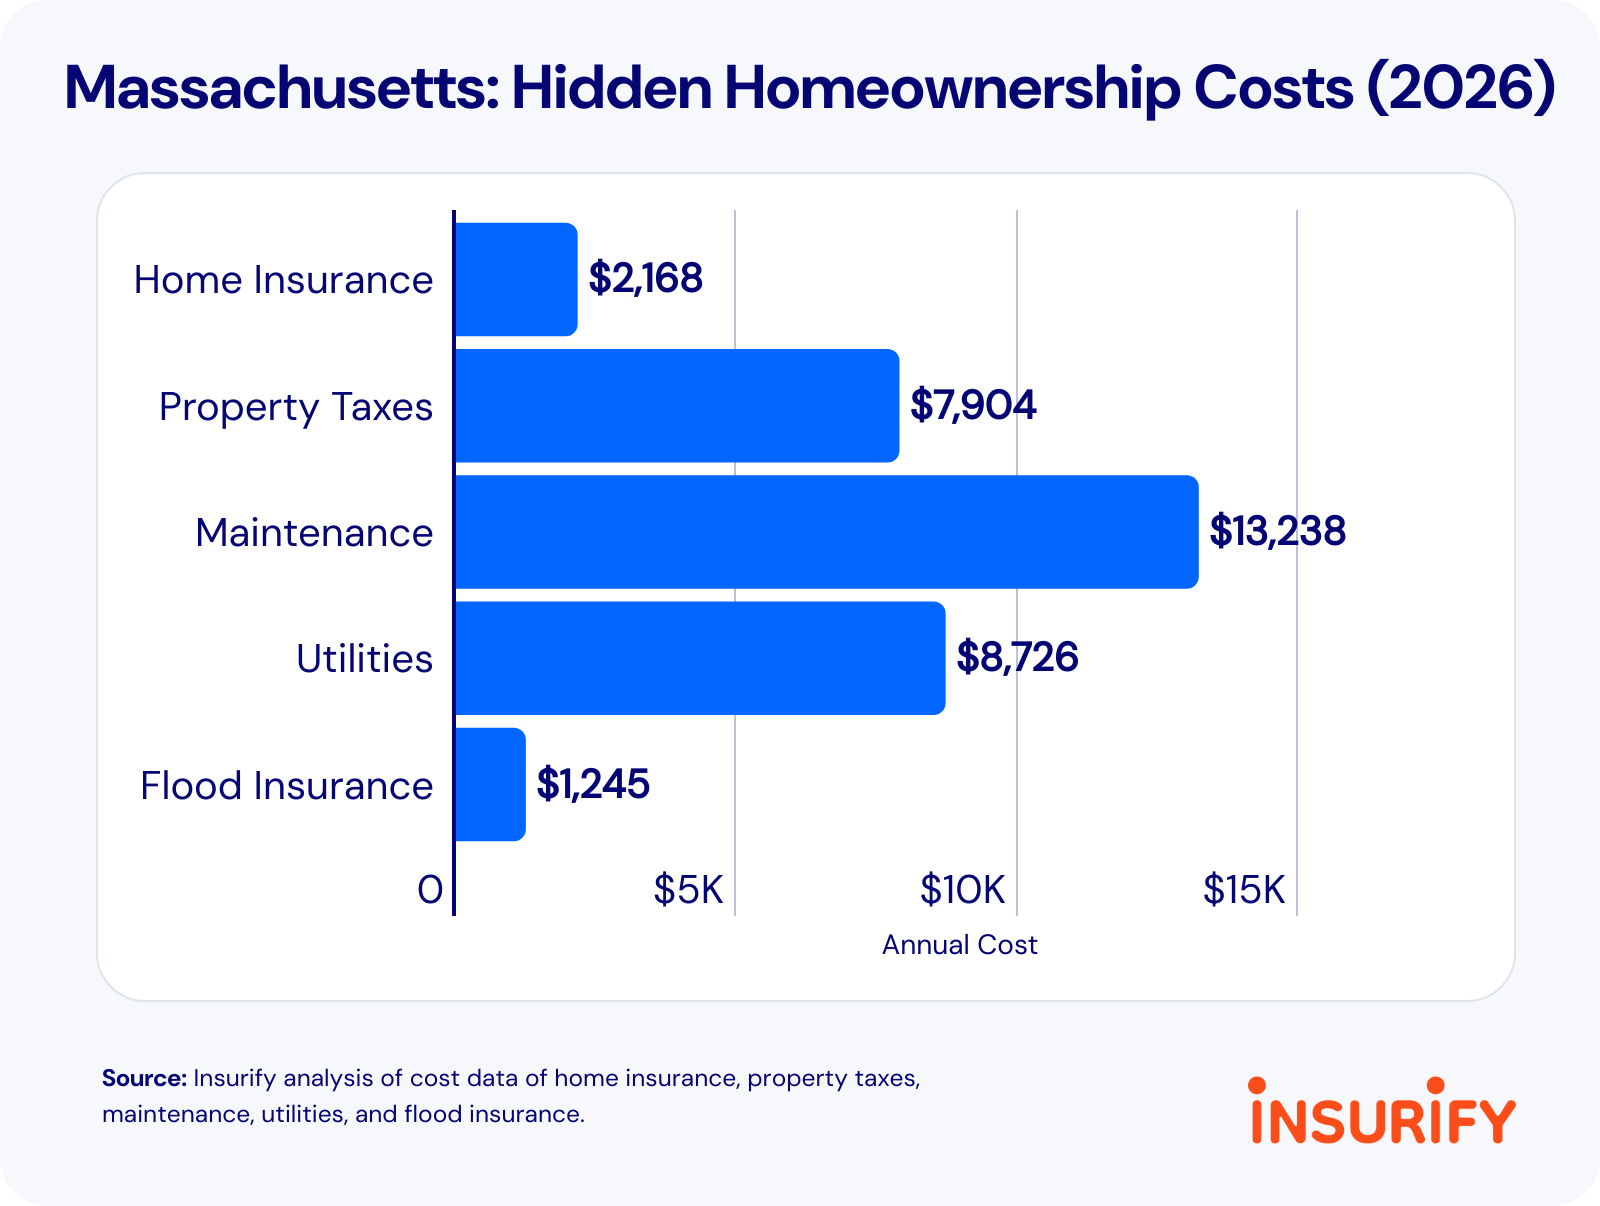
Massachusetts$33,281$2,168$7,904$13,238$8,726$1,245
Michigan$17,566$2,237$3,388$5,326$5,747$868
Minnesota$21,490$3,987$4,114$7,015$5,213$1,161
Mississippi$14,862$3,624$1,563$3,952$4,500$1,223
Missouri$16,753$2,840$2,522$5,358$4,557$1,476
Montana$20,031$2,454$3,031$9,435$4,146$965
Nebraska$18,774$3,987$3,834$5,613$4,339$1,001
Nevada$19,693$1,698$3,014$8,841$5,194$946
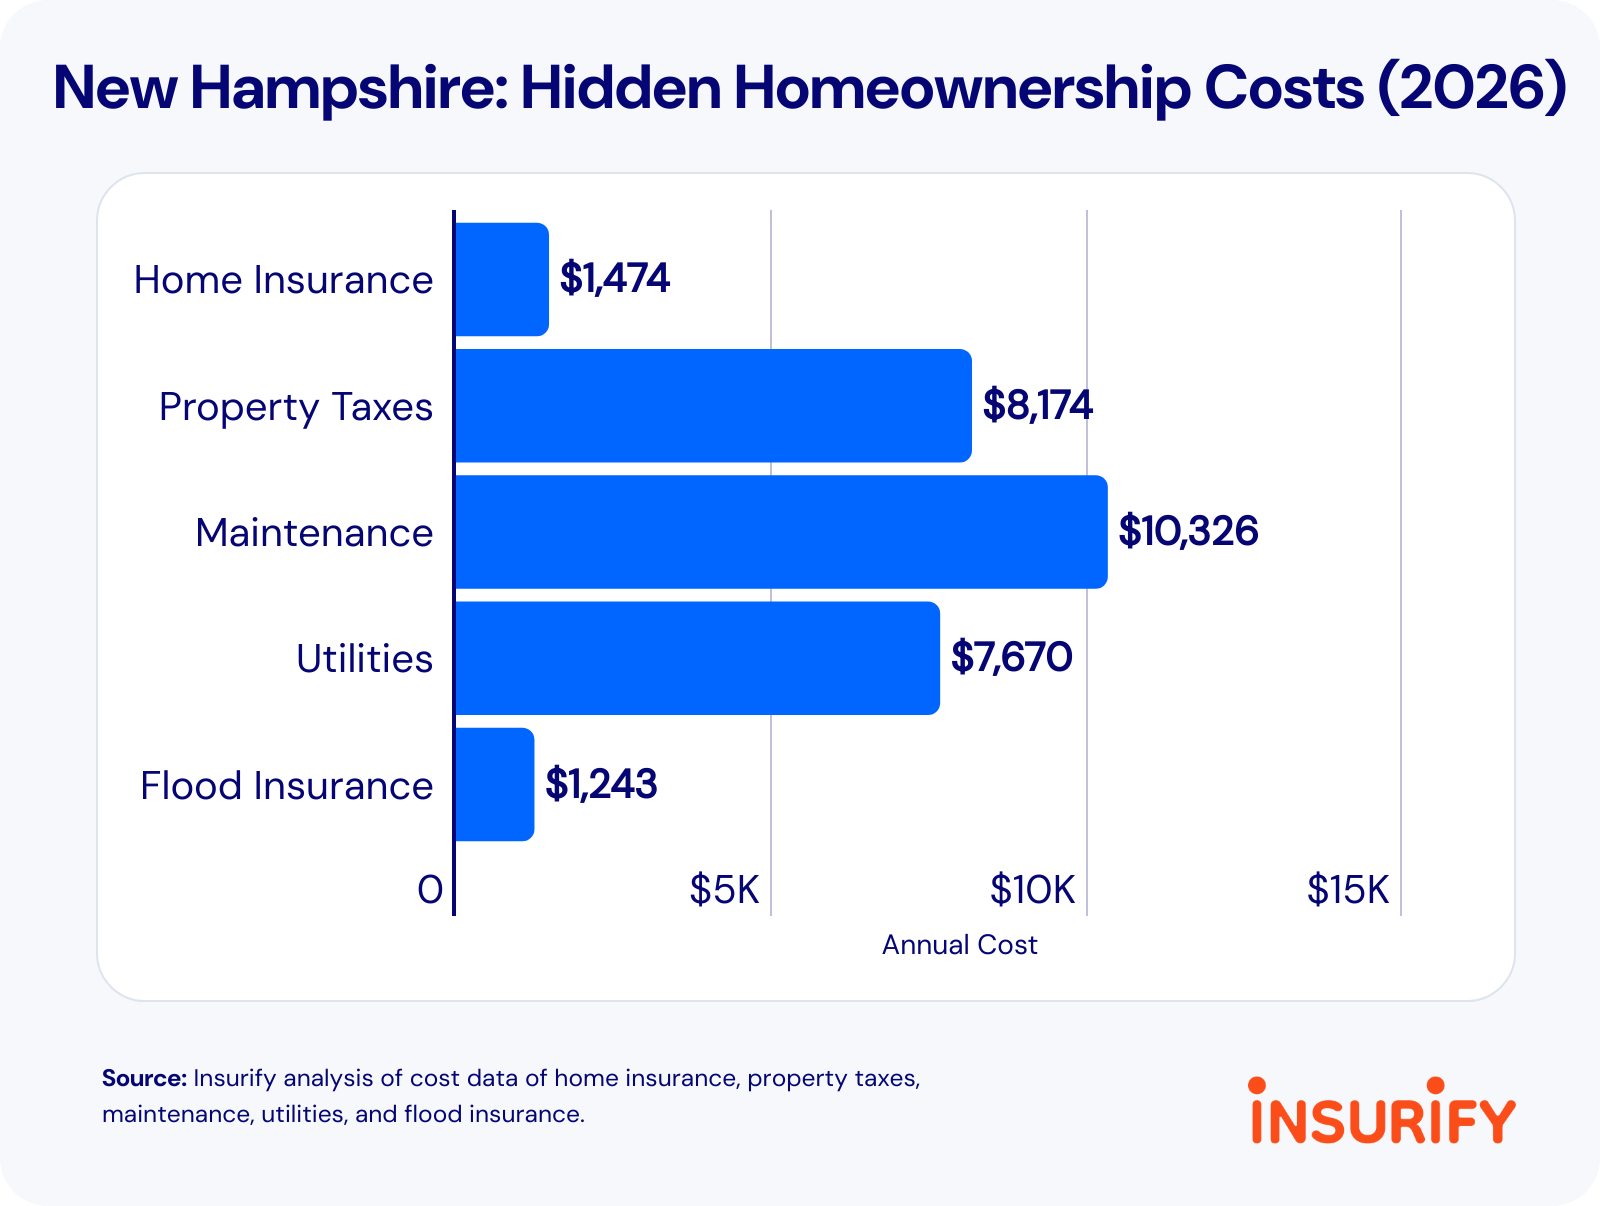
New Hampshire$28,887$1,474$8,174$10,326$7,670$1,243
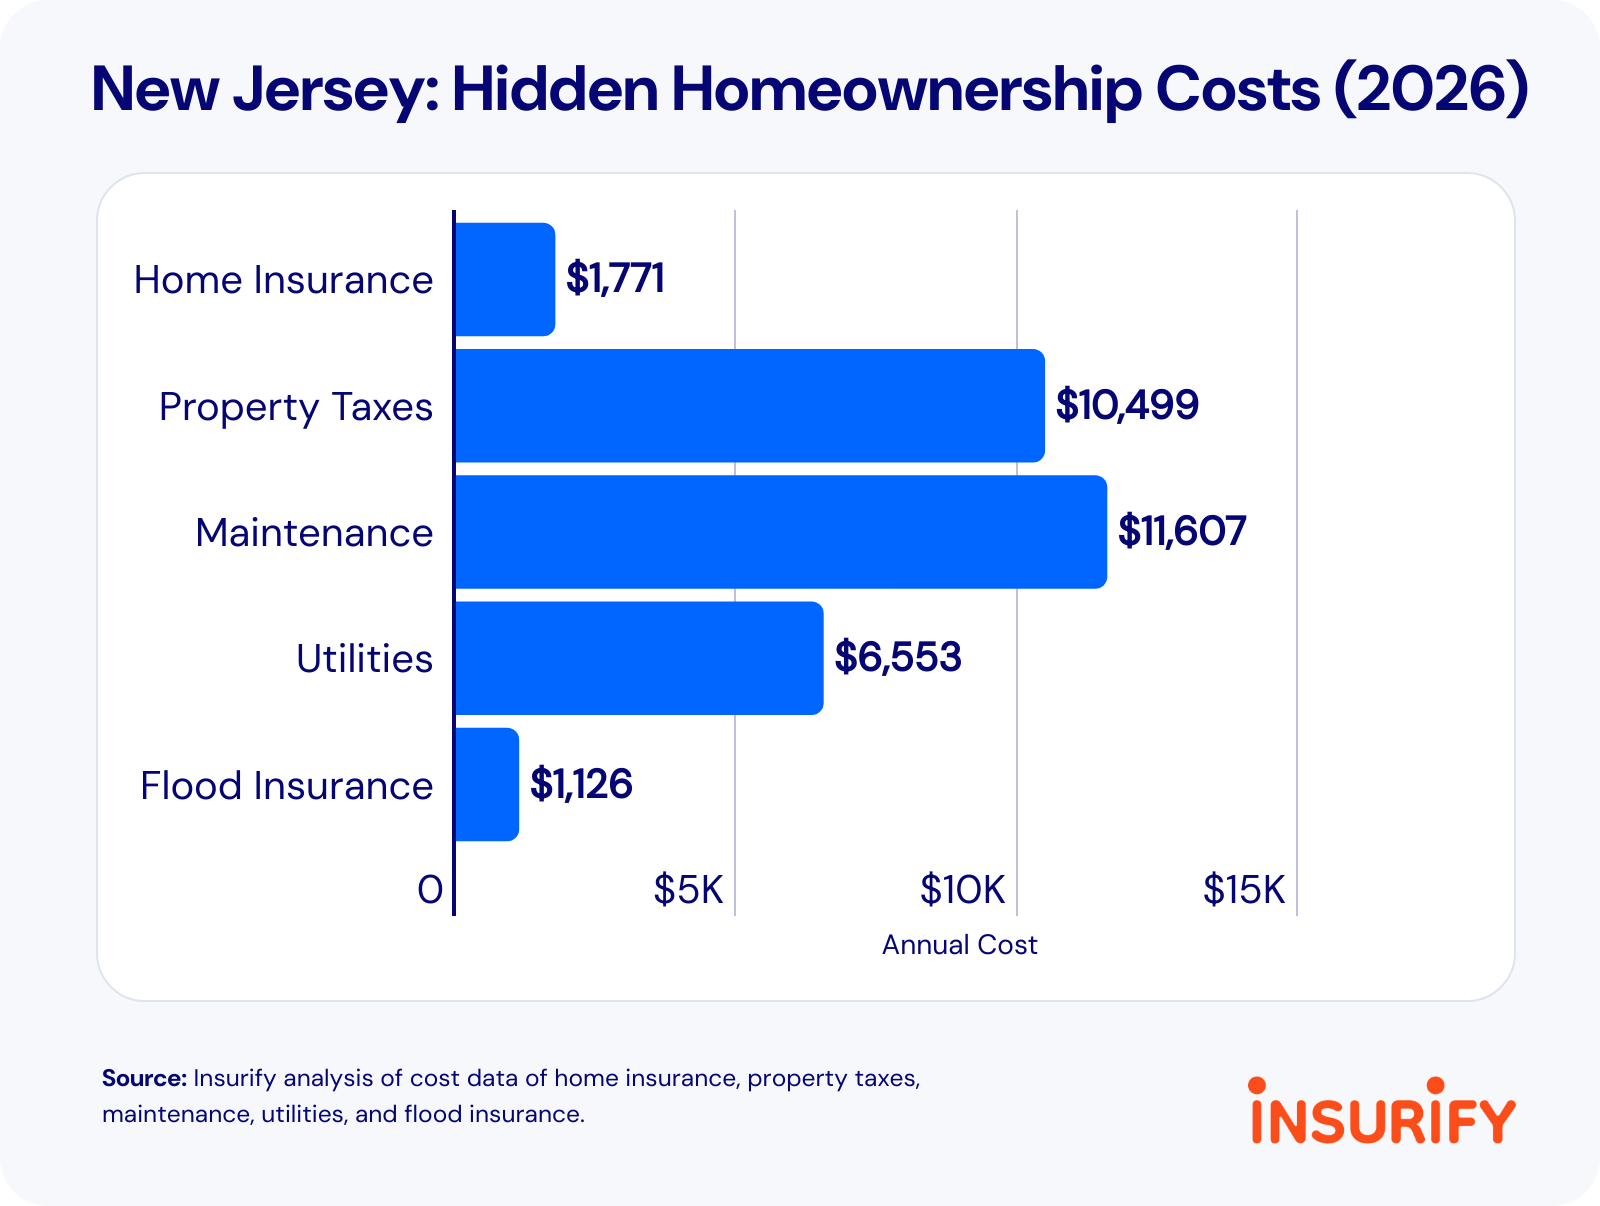
New Jersey$31,556$1,771$10,499$11,607$6,553$1,126
New Mexico$16,755$2,338$2,389$6,365$4,470$1,193
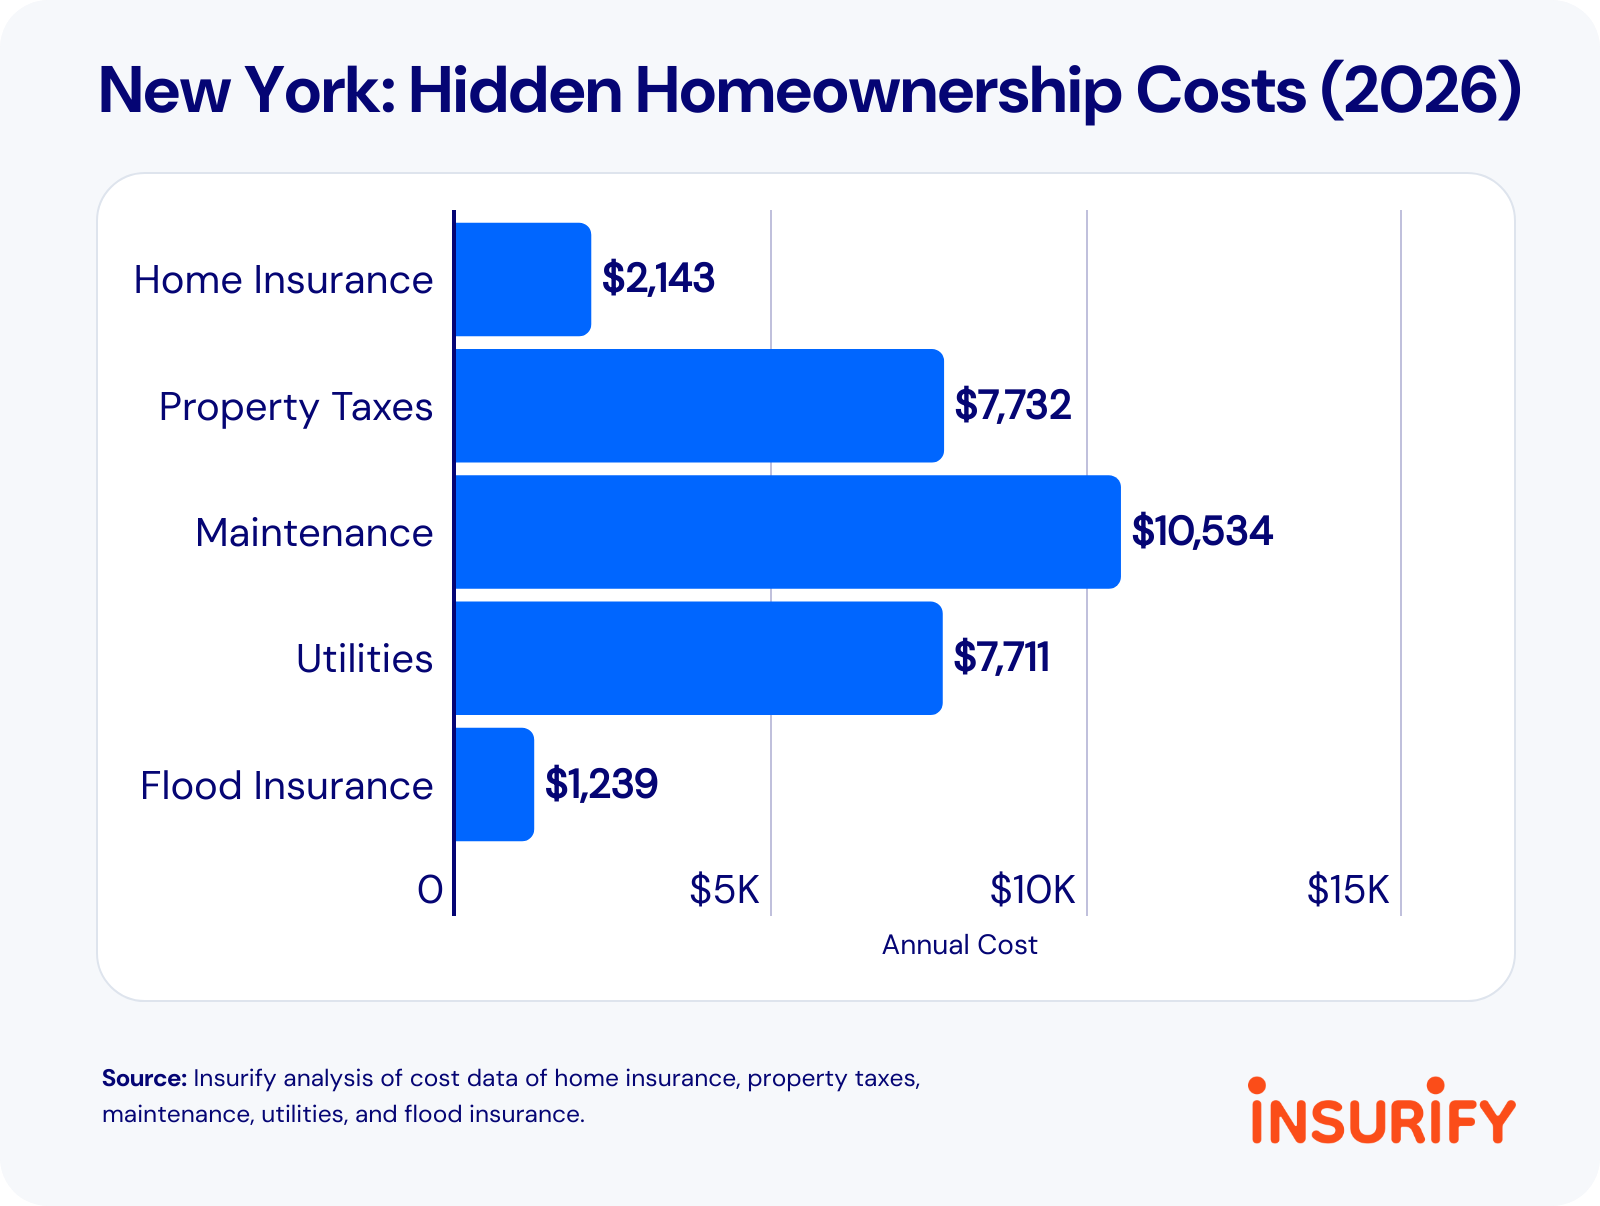
New York$29,359$2,143$7,732$10,534$7,711$1,239
North Carolina$18,738$3,345$2,685$6,695$5,085$928
North Dakota$16,167$2,464$2,747$5,846$4,227$883
Ohio$17,038$1,653$3,793$4,976$5,499$1,117
Oklahoma$16,882$4,919$2,146$4,465$4,240$1,112
Oregon$23,551$1,489$5,006$9,922$6,143$991
Pennsylvania$19,737$1,739$4,366$5,808$6,273$1,551
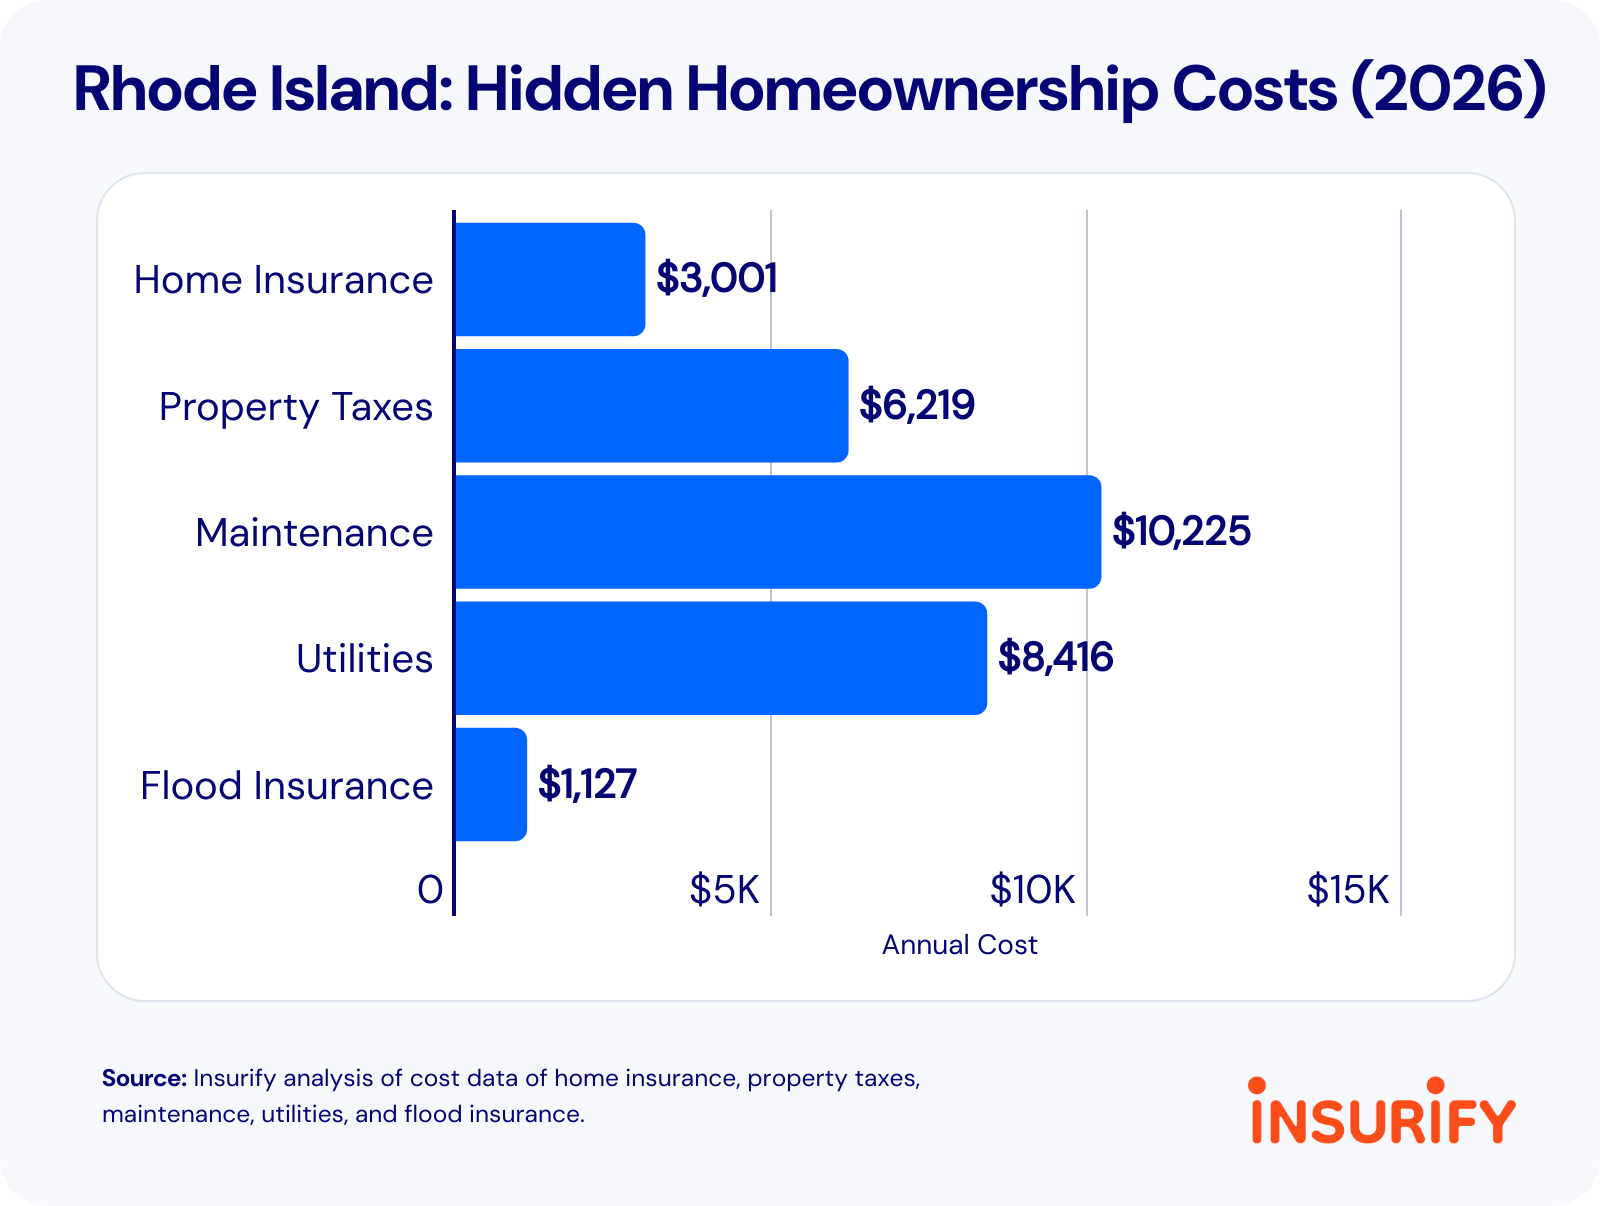
Rhode Island$28,988$3,001$6,219$10,225$8,416$1,127
South Carolina$17,430$3,264$2,187$6,126$5,067$786
South Dakota$18,598$2,757$3,601$6,431$4,571$1,238
Tennessee$17,009$2,948$1,979$6,682$4,140$1,260
Texas$20,990$4,560$4,414$5,987$5,022$1,007
Utah$20,504$1,338$3,261$10,692$4,518$695
Vermont$25,003$1,080$6,991$7,981$7,221$1,730
Virginia$20,071$1,774$3,929$8,293$5,290$785
Washington$25,721$1,587$5,907$11,838$5,329$1,060
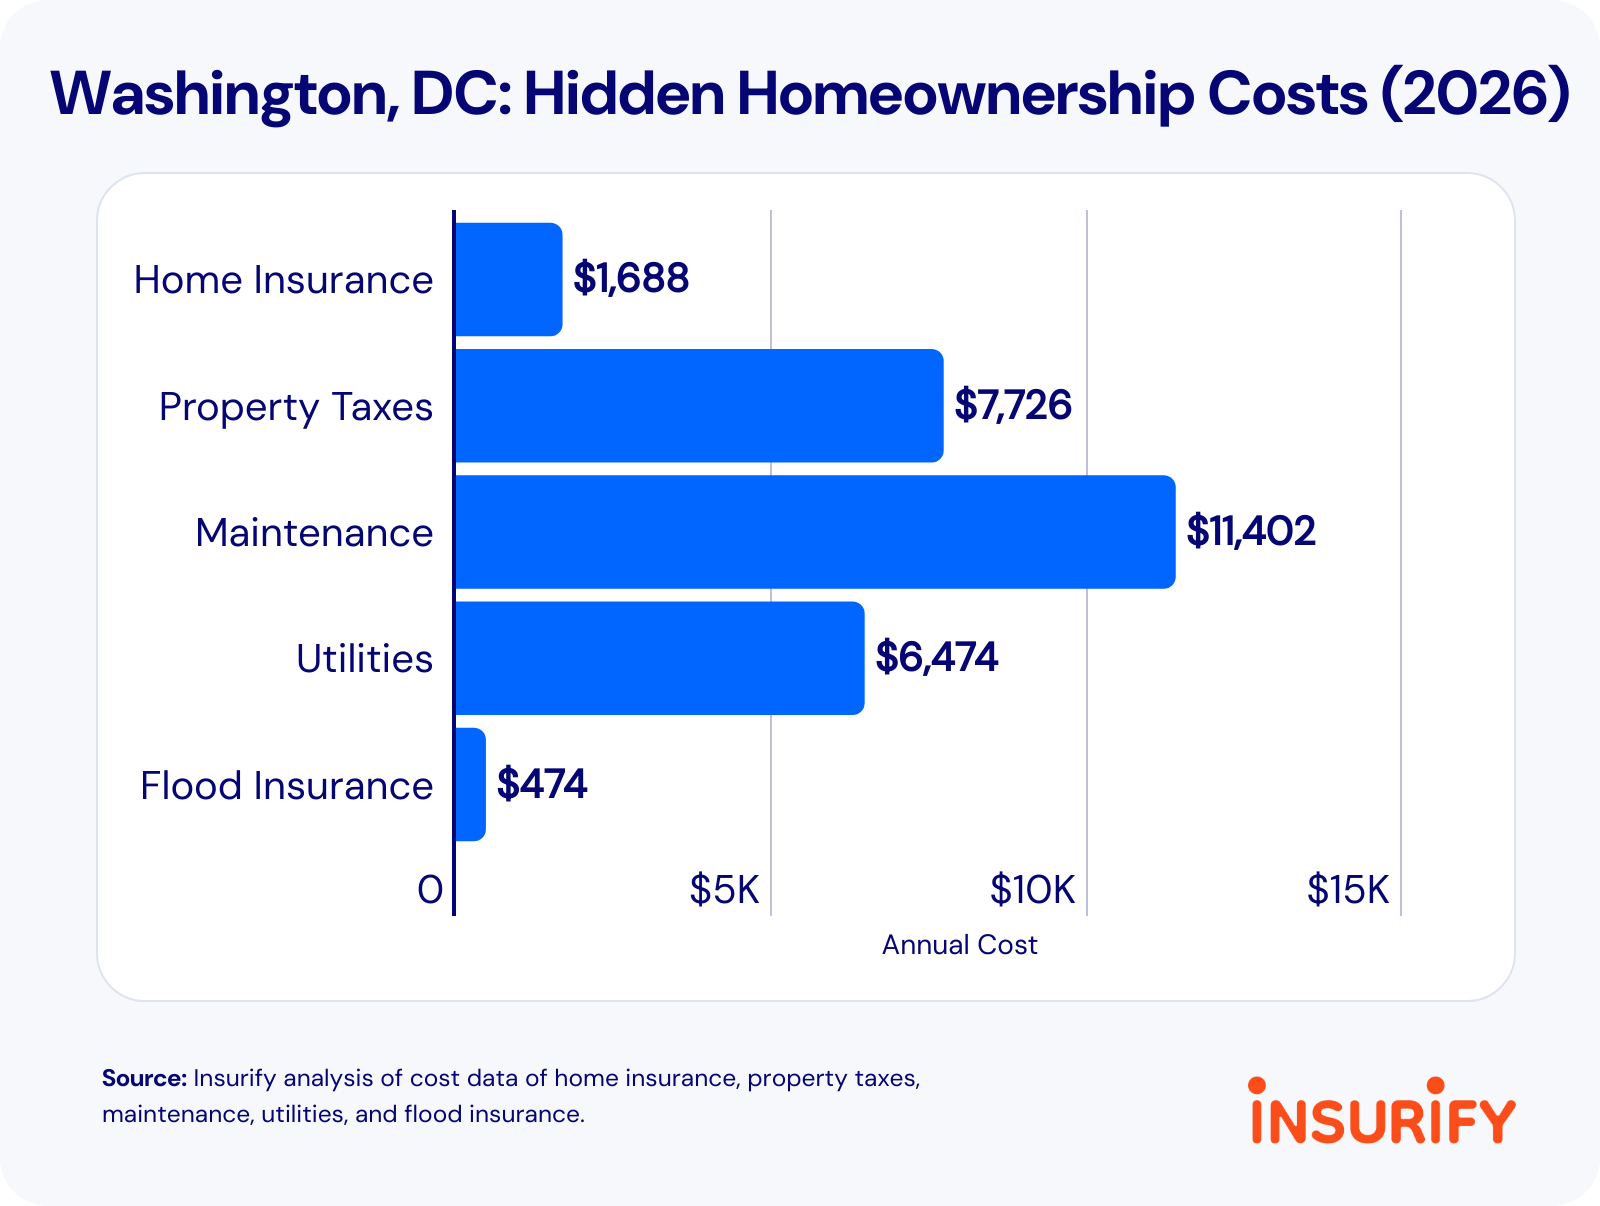
District of Columbia$27,764$1,688$7,726$11,402$6,474$474
West Virginia$13,462$1,589$1,081$3,590$5,293$1,909
Wisconsin$18,772$1,624$4,196$6,794$5,159$999
Wyoming$17,559$1,929$2,695$7,437$4,500$998

Insurify analysis shows where homeownership costs are growing the fastest, based on the total annual cost of maintenance, property tax, utilities, and home and flood insurance. Twelve states have seen hidden costs rise $1,000 or more since 2025.

States that have seen homeownership costs rise sharply in the past year often owe the hike to home insurance premiums. South Carolina had its hidden homeownership costs jump 9.1%, from $15,982 to $17,430, with insurance premiums driving the bulk of that increase. The average cost of home insurance in South Carolina has soared 41% in the past year, according to Insurify analysis. Minnesota’s home insurance costs rose 56%, as insurers respond to more claims from severe weather.

State
Total Year-Over-Year Change
2026 Total
South Carolina9.1% (+$1,448)$17,430
Minnesota9.0% (+$1,770)$21,490
West Virginia8.8% (+$1,089)$13,462
Nebraska7.7% (+$1,342)$18,774
Illinois7.1% (+$1,435)$21,589

Florida remains the most expensive state for home insurance, with an average annual cost of $8,486. Hawaii is the most expensive state both for home maintenance ($16,667) and for utilities ($10,913). New Jersey is the most expensive for property taxes ($10,499), and West Virginia is the most expensive for flood insurance ($1,909).

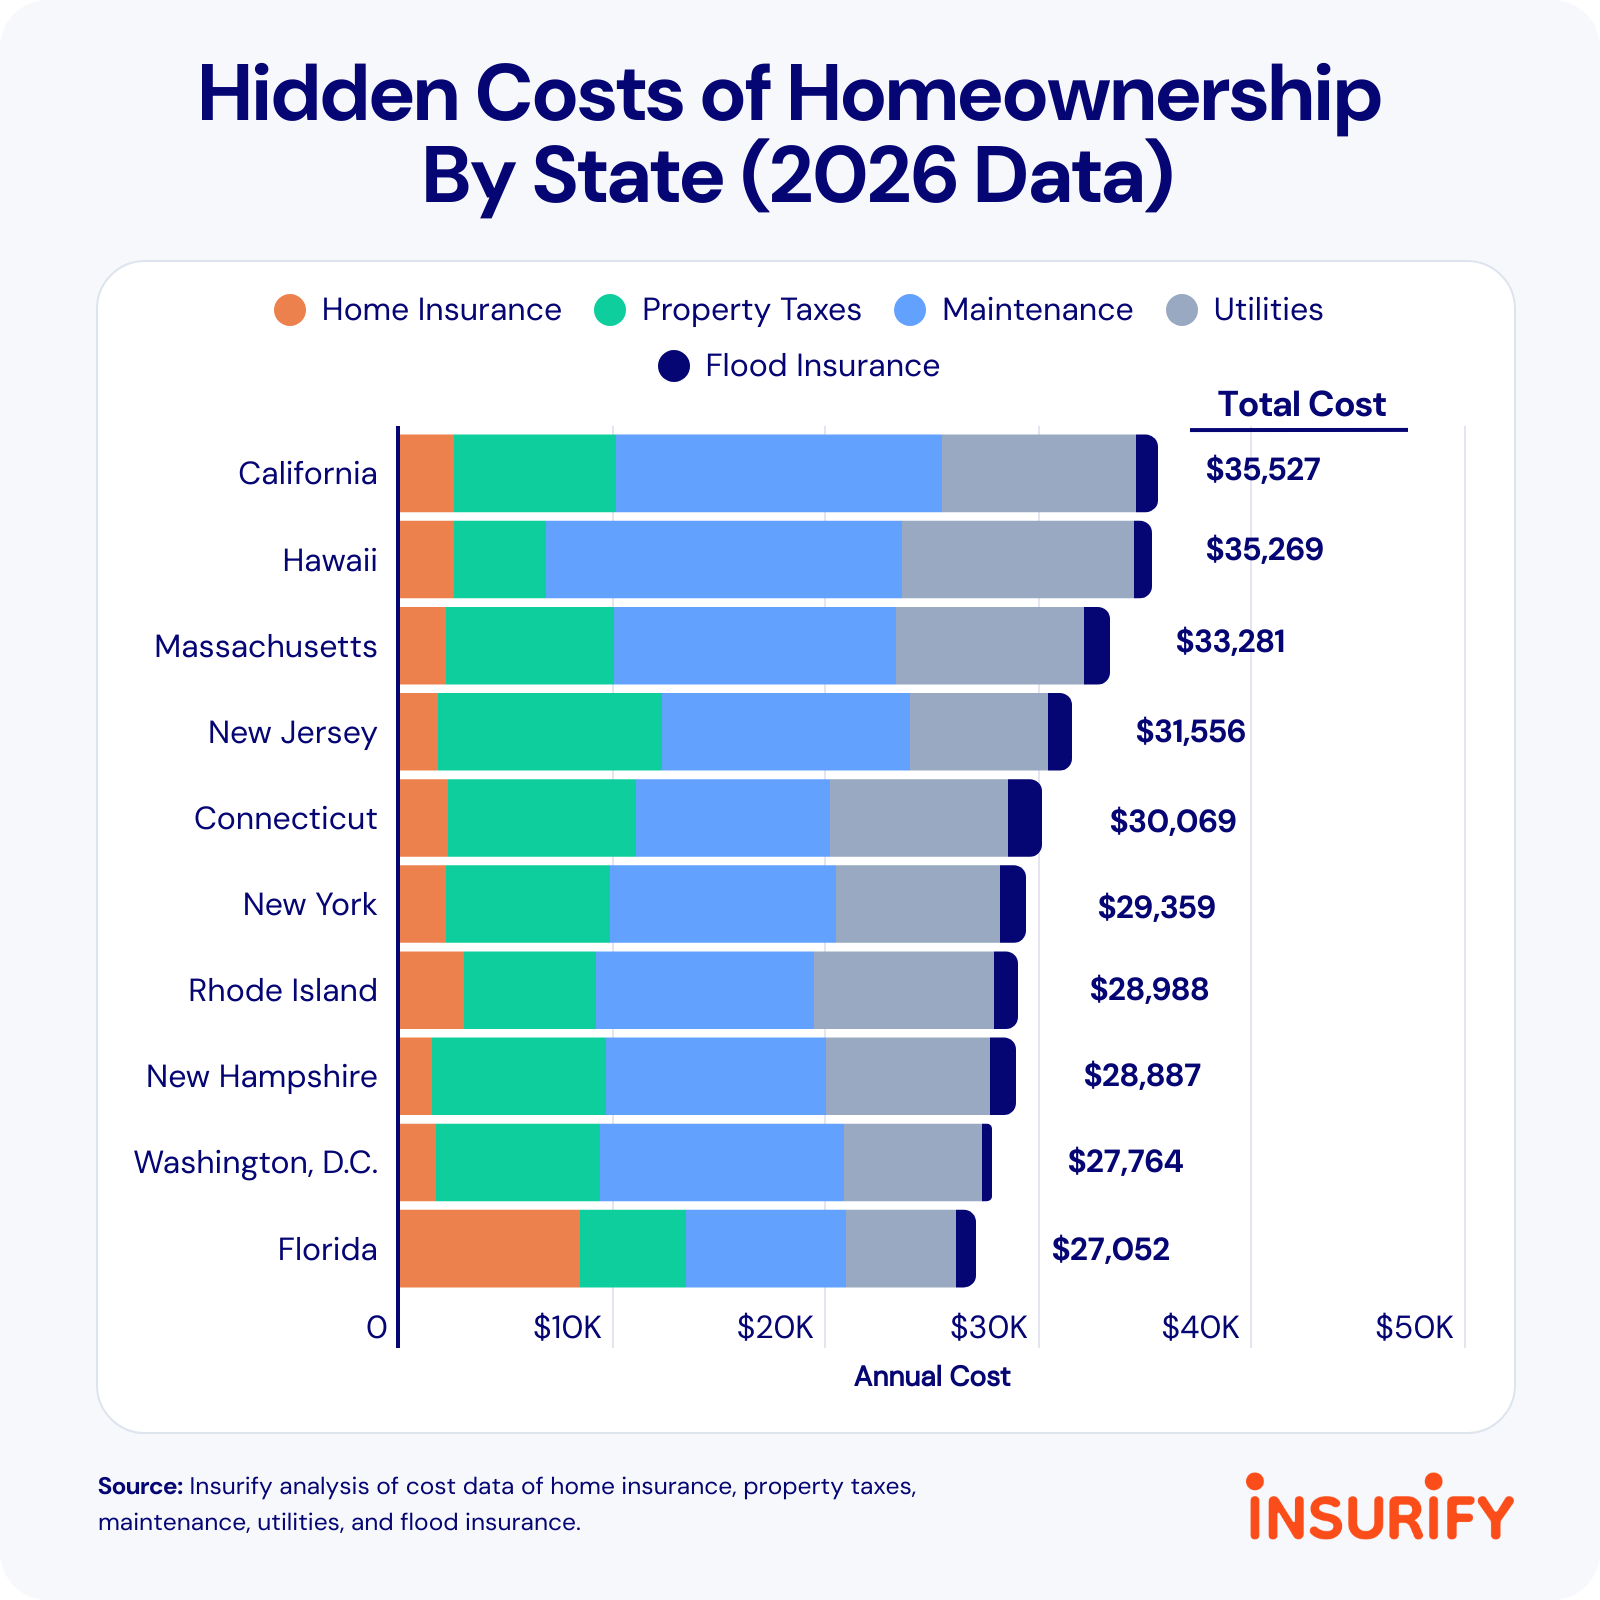
10 states with the most expensive homeownership costs

Geographically, residents in the West and Northeast often pay the most in hidden homeownership costs. These costs surpass $35,000 annually in California and Hawaii. Insurify’s findings show how even homeowners who have paid off their mortgages could end up spending a significant chunk of their income or savings to remain in their homes.

Newer homeowners have even more work cut out for them, even after accounting for closing and moving costs, mortgage principal and interest, and PMI payments until they build sufficient equity. However, potential homebuyers have some control over how their hidden costs tally up. For example, buying a smaller home could help them spend less on utilities, and buying in an area with less extreme weather could mean lower home insurance premiums.
1. California

  • Average annual hidden homeownership cost: $35,527

  • Change in cost since 2025: +4% (+$1,466)

  • Typical home value: $764,158

California homeowners face the most expensive hidden costs of any state. High home values and natural disasters play a big part in those costs. Home insurance rates have risen 8% since last year, after the Palisades and Eaton fires hit Los Angeles County in January 2025.

California has the second-highest utility costs. Electricity rates among some of the state’s largest utilities nearly doubled from 2014 to 2024.[8] State officials point to wildfire mitigation and liability costs as a top driver of the increase.

Homeowners who haven’t yet accrued 20% equity in their home are likely paying for PMI, which costs about $4,126 in California, more than double the national average, according to Insurify’s analysis of Freddie Mac data.

2. Hawaii

  • Average annual hidden homeownership cost: $35,269

  • Change in cost since 2025: +2% (+$530)

  • Typical home value: $833,340

Hawaii homeowners need a big budget to keep up with hidden costs. Utility costs are a major culprit, with homeowners spending about double the national average ($10,913 vs. $5,649), according to an Insurify analysis of Bureau of Labor Statistics data. Electricity costs are higher because the state relies far more on oil imports, and the islands have separate grids, so they can’t share power.[9]

Estimated maintenance costs for Hawaii are the highest in the nation, based on the typical home value. Repairs can run expensive, as Hawaii has the highest construction material costs in the nation.[10] Expensive home materials are also associated with higher home insurance rates.

Newer homeowners in Hawaii may need to spend an additional $4,500 on average to afford PMI until they build sufficient equity.

3. Massachusetts

  • Average annual hidden homeownership cost: $33,281

  • Change in cost since 2025: -1% (-$378)

  • Typical home value: $661,896

The hidden costs of homeownership in Massachusetts come in at over $33,000, driven primarily by maintenance, utilities, and property taxes. New England states often have high utility costs, as they rely heavily on natural gas and the region has limited pipeline capacity.[11] As a result, local homeowners pay $8,726 annually for utilities, 54% above the national average ($5,649).

Massachusetts homeowners also pay the fourth most in annual property taxes ($7,904), with Boston residents in particular paying nearly five figures, at $9,442, according to ATTOM data. Newer homeowners who have to pay for PMI spend an estimated $3,574.

Home insurance is one expense where Massachusetts homeowners catch a slight break. They pay about $2,168 annually for home insurance, well below the national average of $3,012, partly because of less severe weather.

4. New Jersey

  • Average annual hidden homeownership cost: $31,556

  • Change in cost since 2025: +4% (+$1,132)

  • Typical home value: $580,353

Owning a house in New Jersey comes with several hidden costs, with property taxes standing out as a major contributor. It’s the only state where homeowners spend over $10,000, on average, on annual property taxes.

Policy experts say many towns in New Jersey have fewer places (e.g., businesses) to pull tax revenue from, resulting in more public services relying on property tax money. Residents in Bergen County, just outside Manhattan, pay $14,443 annually on average, the most of any county in the U.S.

New Jersey houses tend to require a large maintenance budget as well, coming in at $11,607, in part because of higher construction material costs.

Meanwhile, homeowners who are still working toward building 20% equity in their home are likely paying for PMI, which averages $3,134 annually in New Jersey.

5. Connecticut

  • Average annual hidden homeownership cost: $30,069

  • Change in cost since 2025: +1% (+$292)

  • Typical home value: $450,873

Connecticut homes tend to require less maintenance spending than most states on this list but still end up with hidden homeownership costs exceeding $30,000. The state ranks among the top five nationally for most expensive property taxes, most expensive flood insurance, and most expensive utilities.

Connecticut homeowners may be surprised to see how much flood insurance can cost, but Hurricane Sandy in 2012 highlighted the state’s exposure to flooding. That year, the NFIP paid out more than $263 million in flood insurance claims in Connecticut.[12]

Recent buyers who may still be paying PMI face an additional annual cost of $2,435, on average, until they build 20% equity in their home.

6. New York

  • Average annual hidden homeownership cost: $29,359

  • Change in cost since 2025: +3% (+$722)

  • Typical home value: $526,714

New York has the sixth-highest hidden cost of homeownership, at just under $30,000 annually. The average costs of home insurance and flood insurance in New York are each up 8% in the past year.

Heavy rains can drive up the cost of flood insurance. Suffolk County incurred $41 million in damage following record rainfall in August 2024.[13] Additionally, a high population of coastal residents means more exposure to windstorm damage, contributing to more expensive home insurance premiums.

New York has the fifth-highest property taxes on average, at $7,732. In fact, the five priciest states for property taxes are all in the Northeast. For New York homeowners still trying to reach 20% equity, Insurify expects that PMI would run an extra $2,844 annually, based on Freddie Mac data.

7. Rhode Island

  • Average annual hidden homeownership cost: $28,988

  • Change in cost since 2025: +4% (+$1,111)

  • Typical home value: $511,233

Hidden costs run high in Rhode Island in part because homeowners spend about $8,416 annually on utilities, the fourth most of any state. As a region, New England relies more on natural gas to generate electricity, which can cause higher utility bills.[14] All six New England states rank among the top 10 for utility costs, and all rank within the top 15 overall for total hidden homeownership costs.

Rhode Island is also the 10th most expensive state for property taxes and 11th most expensive for maintenance. Recent homebuyers may also need to pay for mortgage insurance or PMI, which would add $2,761 per year on average, raising the total potential hidden cost to $31,749.

8. New Hampshire

  • Average annual hidden homeownership cost: $28,887

  • Change in cost since 2025: 0% (+$1)

  • Typical home value: $516,306

New Hampshire has the eighth most expensive hidden homeownership costs. The state ranks third for most expensive property taxes. Property taxes shoulder more of the general tax burden in the area, as New Hampshire is one of nine states with no income tax.[15]

New Hampshire also ranks eighth highest nationally for annual utility costs ($7,670). In the past, state officials have said that roughly half the electricity supplied in New Hampshire stems from natural gas. When cold spells hit, natural gas for heating takes up pipeline space, lowering supply of gas for electricity and raising its cost.[16]

In addition to these hidden homeownership costs, new homeowners specifically spend about $2,788 annually on PMI.

9. Washington, D.C.

  • Average annual hidden homeownership cost: $27,764

  • Change in cost since 2025: N/A

  • Typical home value: $570,119

Hidden homeownership costs are quick to add up in Washington, D.C. If it were a state, it would rank sixth highest nationally for property taxes ($7,726 annually). D.C.’s urban setting is partially responsible for that cost, as home values tend to be higher in cities than suburbs or rural areas.[17] And property taxes are based in part on home values, resulting in D.C. homeowners paying more than the typical American in property taxes.

One bright spot: Home insurance premiums are about half the national average in D.C. ($1,688 vs. $3,012), in part because the area sees less extreme weather than others. PMI, meanwhile, can run new homeowners about $3,079 annually.

10. Florida

  • Average annual hidden homeownership cost: $27,052

  • Change in cost since 2025: 0% (-$80)

  • Typical home value: $375,470

Florida homeowners can expect to pay more than $27,000 annually in hidden costs. It’s one of three states where home insurance is the most expensive hidden cost, the others being Louisiana and Oklahoma. It’s also the most expensive state for home insurance nationally (averaging $8,486 annually), in large part due to the state’s vulnerability to hurricanes.

Hurricane risk can also drive up the cost of flood insurance, which rose 9% in Florida over the past year for an NFIP policy. In a particularly hurricane-prone 2024, Florida accounted for 80% of paid NFIP claims in the U.S.

Those newer to homeownership in Florida are likely still paying PMI, too, which costs an estimated $2,028 annually in the state.

High home insurance deductibles add more financial pressure

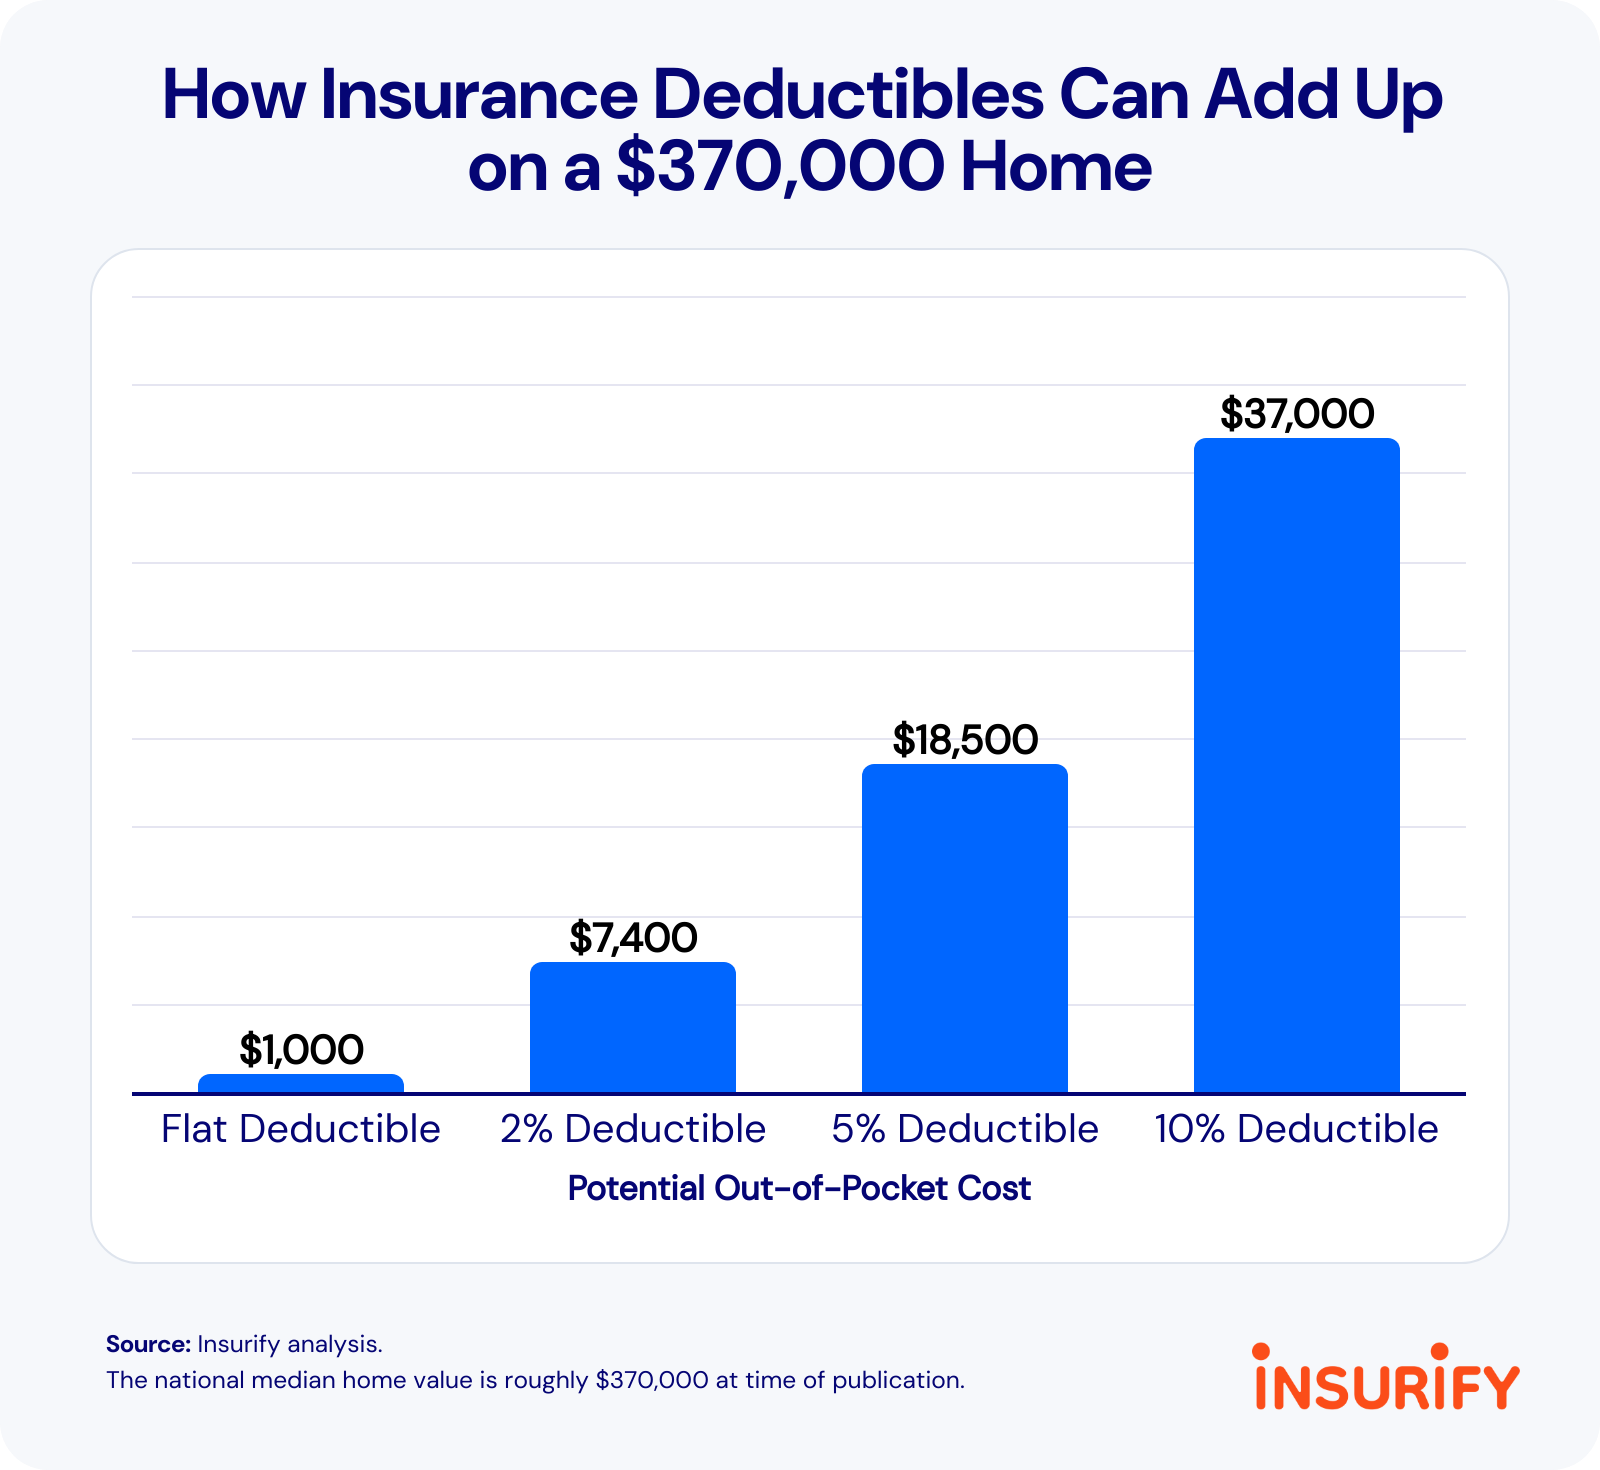
While home insurance premiums are a recurring cost, homeowners can also face sporadic expenses like the deductibles on insurance claims. Deductibles are the amount the homeowner pays out of pocket after filing a claim and before insurance kicks in. Sometimes this is $1,000, depending on the policy, but the amount can also be a percentage of the home’s dwelling coverage.

Policies for homes at higher risk of hail, for example, might have homeowners pay 2% of the home’s dwelling value before the policy pays out. In a home with $370,000 of dwelling coverage, that means a homeowner has to pay for the first $7,400 in damage.

Similarly, for especially destructive perils, a policy might specify that homeowners must cover higher percentages, like 5% of the dwelling value for windstorm damage in hurricane-prone areas or 10% on earthquake insurance. In those scenarios, homeowners with $370,000 in dwelling coverage could end up paying $18,500 or $37,000 out of pocket before their insurer pays for damage.

Tips: How homeowners can deal with high homeownership costs

With hidden homeownership costs totaling more than $21,000 on average, homeowners should know they can take steps to mitigate those costs.

  • Home insurance: Insurance rates can be volatile, so homeowners should get quotes from multiple companies before renewing. Comparing policies across insurers can save homeowners up to 47% on premiums. People about to buy a home benefit from comparing quotes ahead of time to help understand the full costs of homeownership.

  • Flood insurance: Flood premiums are based on multiple different risk factors, some of which homeowners can influence. The NFIP mentions installing flood openings, elevating the property, or filling in basements to lower risk and possibly premiums.[18]

  • Utilities: Homeowners can benefit from energy-efficient changes to a home. The Department of Energy notes switching from incandescent to LED bulbs can save $200 annually, and programmable thermostats can further cut unnecessary energy use when a homeowner is away.[19]

  • Maintenance: Homeowners shouldn’t put off smaller maintenance problems that can become bigger headaches. Even peeling exterior paint can make the home more susceptible to water damage.[20] And when hiring contractors for repairs, it’s worthwhile to get at least three quotes before moving forward.

  • Property taxes: Homeowners can attempt to reduce their property taxes by appealing the assessed value of their home through their county or city assessor’s office. Certain states offer property tax relief for seniors, as well.[21]

Methodology

Insurify data scientists turned to their real-time database of insurance quotes from partner carriers, as well as aggregated rate filings from Quadrant Information Services, to determine average home insurance costs. Unless otherwise stated, home insurance rates in this report represent the average annual cost of an HO-3 insurance policy for homeowners with good credit and zero claims within the past five years, covering a single-family frame house with the following coverage limits: $200,000 to $750,000 dwelling coverage depending on the locality’s typical home value, $25,000 personal property, $30,000 loss of use, $300,000 liability, and a $1,000 deductible. Certain states also include a 2% hail deductible and/or a 5% wind/hurricane deductible.

Average property tax rates for single-family homes come from ATTOM, a real estate data firm, using the most recent available data as of May 2026. Annual maintenance and repair costs are based on a 2% estimate of the home’s value, in line with industry recommendations of budgeting 1% to 4%.[22] Home values come from the Zillow Home Value Index.[23]

Utility costs use a baseline U.S. average of $5,649 for homeowners, according to the Bureau of Labor Statistics. Factors include electric, natural gas, fuels, telephone, water, and other public services. Utility costs were then adjusted by state and city based on regional price parities for utility services, according to the Bureau of Economic Analysis.[24]

Average flood insurance costs for cities and states come from the NFIP’s Policy Information by State dataset, which includes premiums for both residential and commercial properties.[25]

PMI estimates assume a 10% down payment and are based on 0.6% of the remaining loan amount for the typical home’s value, the midpoint of Freddie Mac’s example range.[5]

Washington, D.C., was excluded from the year-over-year cost analysis due to a lack of data across some categories.

Sources

  1. Government Accountability Office. "As Flood Risks Increase, Most Americans Still Don't Have Insurance for It (Interactive Map)."
  2. AP News. "Is El Niño making storms and flash floods in the Southwest worse?."
  3. Federal Reserve. "Consumer Price Index for All Urban Consumers: Housing in U.S. City Average."
  4. Federal Reserve. "30-Year Fixed Rate Mortgage Average in the United States."
  5. Freddie Mac. "What Is Private Mortgage Insurance?."
  6. Census. "Nearly a Quarter of Homeowners Paid Condo or HOA Fees in 2024."
  7. Energy Information Administration. "U.S. electricity prices continue steady increase."
  8. Public Advocates Office. "Q3 2024 Electric Rates Report."
  9. Energy Information Administration. "Hawaii."
  10. Today's Homeowner. "How Much Does It Cost to Build a Home in Each State?."
  11. Department of Energy. "FACT SHEET: The Energy Department is Advancing the Constitution Pipeline to Strengthen National Security and Lower Energy Costs in the Northeast."
  12. Floodsmart. "Historical NFIP Claims Information and Trends."
  13. WSHU. "Suffolk County flash floods cause over $41 million in damages."
  14. Office of Legislative Research. "Factors Behind Connecticut’s High Electric Rates."
  15. Intuit Turbotax. "9 States with No Income Tax."
  16. New Hampshire Department of Energy. "Information Related to High Energy Costs."
  17. Realtor.com. "New-Construction Insights: Urban New Builds Are Scarce and Expensive."
  18. Floodsmart. "Help Clients Pay Less For Flood Insurance."
  19. Department of Energy. "Celebrate National Cut Your Energy Costs Day."
  20. AARP. "How to Save on Home Maintenance Inside and Out."
  21. AARP. "6 Simple Ways to Lower Your Property Tax Bill."
  22. Fannie Mae. "How to Build Your Maintenance and Repair Budget."
  23. Zillow. "Zillow Home Value Index (ZHVI)."
  24. Bureau of Economic Analysis. "Regional Price Parities by State and Metro Area."
  25. Floodsmart. "Flood Insurance Data."
Matt Brannon
Writer: Matt BrannonSenior Economic Analyst, Licensed Insurance Agent

Qualifications:
  • 11+ years in content creation

  • 4+ years in business and financial services content

  • NPN: 22276396


Matt is a senior economic analyst and insurance correspondent at Insurify. His work is cited by media outlets nationwide.

Evelyn Pimplaskar
Editor: Evelyn PimplaskarEditor-in-Chief, Director of Content

Qualifications:
  • 10+ years in insurance and personal finance content

  • 30+ years in media, PR, and content creation


Evelyn leads Insurify’s content team. She’s passionate about creating empowering content to help people transform their financial lives and make sound insurance-buying decisions.