Average Car Insurance Rates as of October 2026

The overall national average cost of car insurance held steady at $143 per month in September.
Doug Bailey
Writer: Doug BaileySenior Content Writer

Qualifications:
  • 15 years at the Boston Globe

  • 5+ years covering insurance industry


Doug joined Insurify as a senior content writer in 2025. He was previously a regular contributor to InsuranceNewsNet.

Evelyn Pimplaskar
Editor: Evelyn PimplaskarEditor-in-Chief, Director of Content

Qualifications:
  • 10+ years in insurance and personal finance content

  • 30+ years in media, PR, and content creation


Evelyn leads Insurify’s content team. She’s passionate about creating empowering content to help people transform their financial lives and make sound insurance-buying decisions.

MacKenzie Korris
Reviewer: MacKenzie KorrisLicensed P&C Agent, Senior Insurance Copy Editor

Qualifications:
  • Licensed property and casualty insurance agent

  • 10+ years editing experience

  • NPN: 21630969


MacKenzie Korris is an insurance copy editor with a producer’s license for property and casualty insurance in Missouri.

Published | Reading time: 4 minutes

Why you can trust Insurify: Comparing accurate insurance quotes should never put you at risk of spam. We earn an agent commission only if you buy a policy based on our quotes. Our editorial team follows a rigorous set of editorial standards and operates independently from our insurance partners. Learn more.

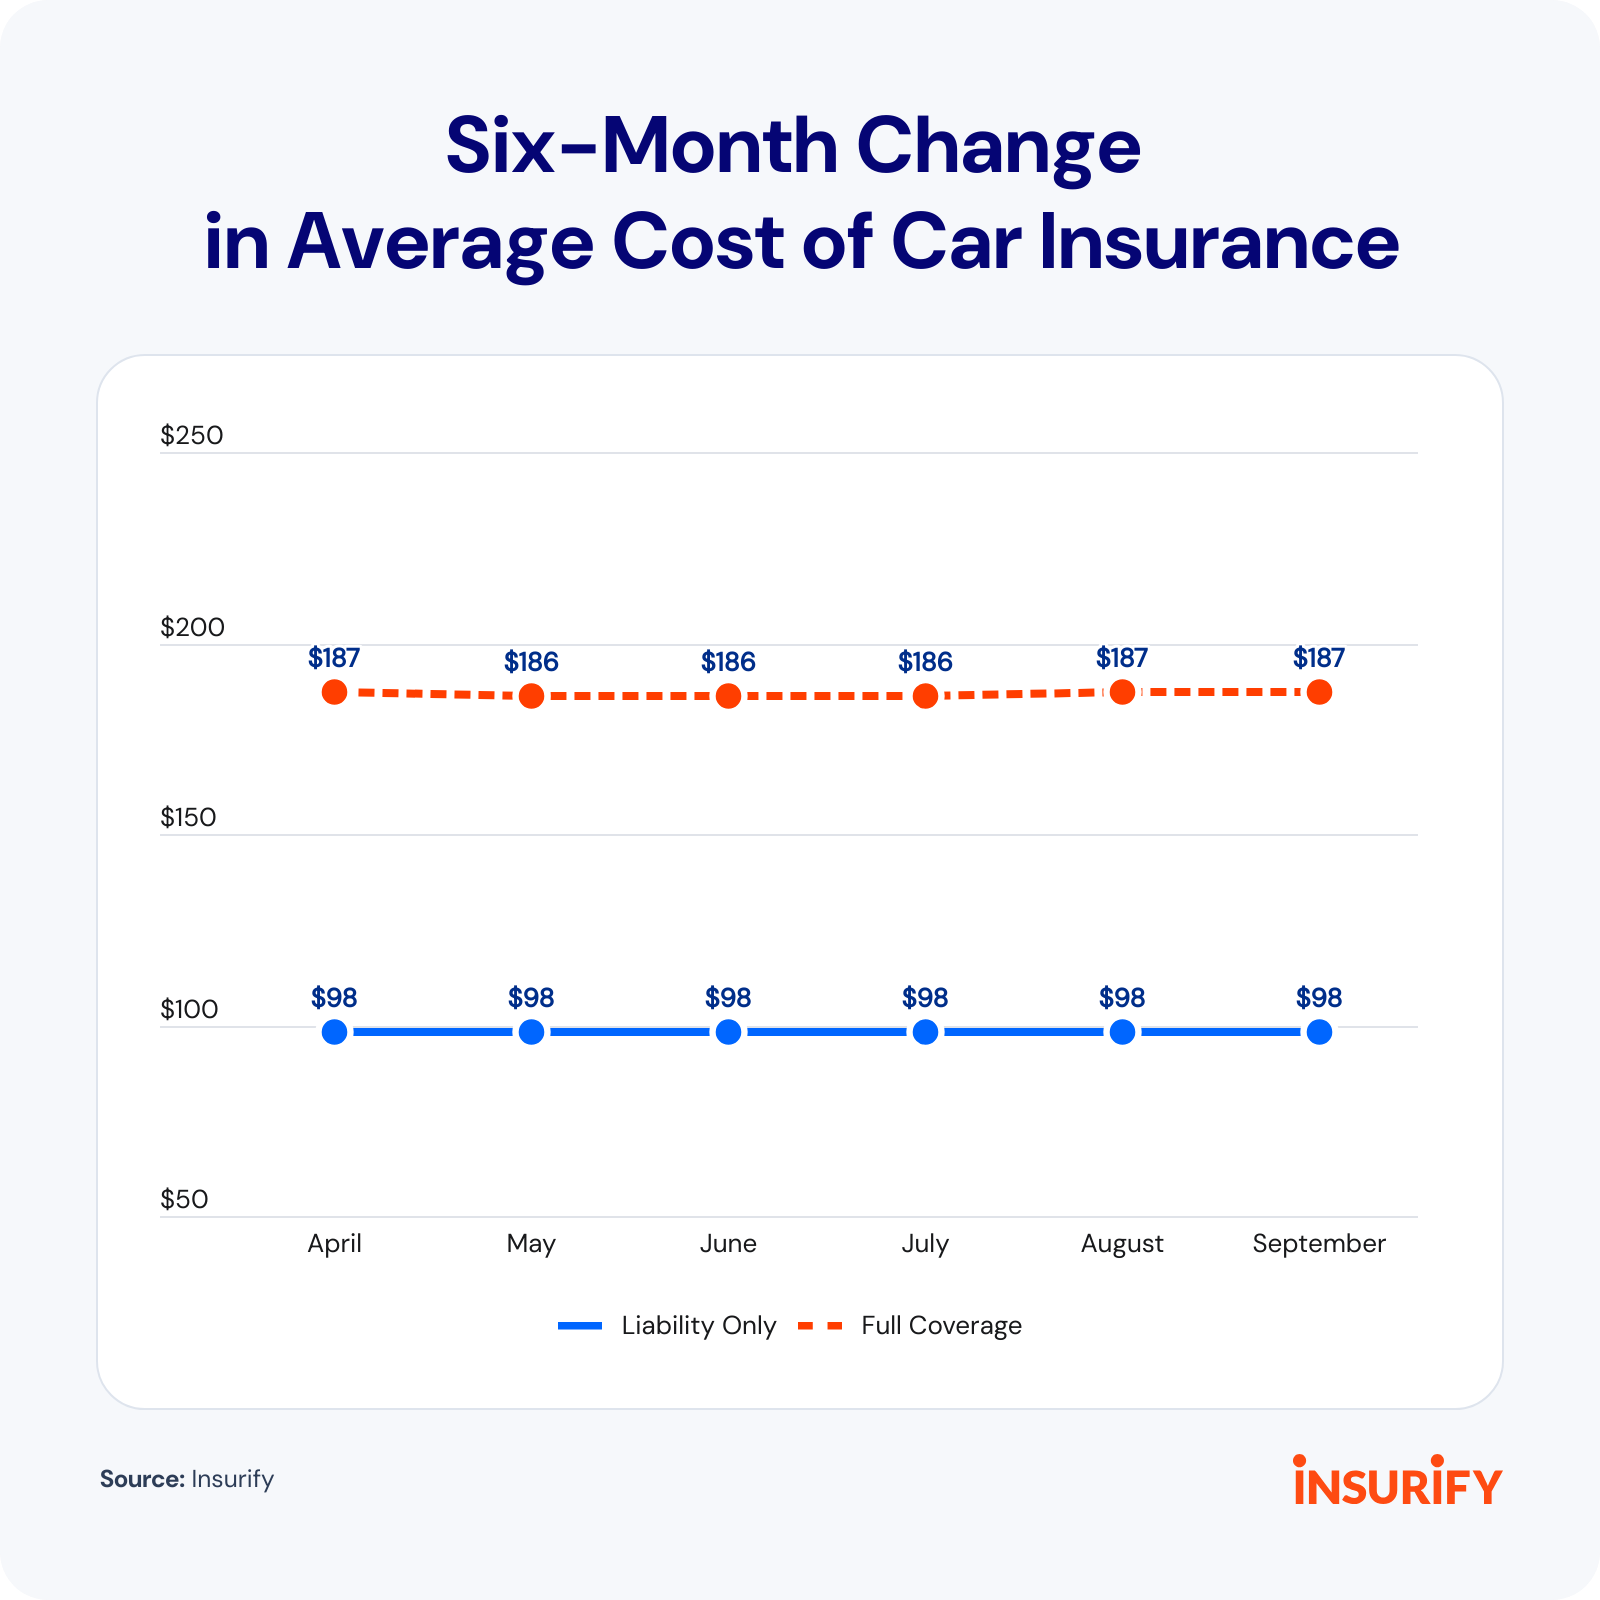
Car insurance rates have largely remained stable throughout the summer and early fall, and that trend continued in September. The national average rate for full-coverage car insurance held steady at $187 per month through August, according to Insurify data. The national average liability rate climbed slightly, from $98 per month to $99.

Average cost of car insurance by state as of September 2026

Insurance rates can vary greatly by location, which influences factors like exposure to extreme weather, repair costs, traffic congestion, and vehicle crime rates.

Here are the monthly averages for full and liability coverage across the country.

State
Full
Liability
National$187$99
Alabama$142$66
Alaska$97$59
Arizona$162$91
Arkansas$150$73
California$203$98
Colorado$217$97
Connecticut$225$162
Delaware$262$166
Florida$236$142
Georgia$259$157
Hawaii$126$62
Idaho$107$64
Illinois$162$84
Indiana$128$64
Iowa$111$56
Kansas$157$79
Kentucky$194$121
Louisiana$209$106
Maine$139$74
Maryland$302$191
Massachusetts$137$103
Michigan$229$130
Minnesota$182$93
Mississippi$186$89
Missouri$180$92
Montana$139$62
Nebraska$134$69
Nevada$260$164
New Hampshire$85$52
New Jersey$257$181
New Mexico$133$65
New York$218$145
North Carolina$113$69
North Dakota$114$66
Ohio$117$65
Oklahoma$169$83
Oregon$156$91
Pennsylvania$162$90
Rhode Island$298$177
South Carolina$255$160
South Dakota$152$62
Tennessee$132$60
Texas$204$110
Utah$146$92
Vermont$140$57
Virginia$207$118
Washington$184$95
Washington, D.C.$237$136
West Virginia$156$83
Wisconsin$125$57
Wyoming$94$50
Disclaimer: All rates displayed in the table are averages of Insurify price data through September 2026. Full-coverage rates represent two-year rolling medians for most states. Liability-only rates — and full-coverage prices for Maine, Massachusetts, Michigan, Montana, North Dakota, Nebraska, New Hampshire, New Jersey, and Vermont — represent one-year rolling averages.

5 states with the highest car insurance rates as of September 2026

Maryland and Rhode Island remain the most expensive locations for car insurance in the nation. The top five for this month remain identical to the previous month.

State
Average Quote: Full Coverage
Average Quote: Liability Only
Overall Average
Maryland$302$191$247
Rhode Island$298$177$238
New Jersey$257$181$219
Delaware$262$166$214
Nevada$260$164$212
Disclaimer: All rates displayed in the table are averages of Insurify price data through September 2026. Full-coverage rates represent two-year rolling medians for most states. Liability-only rates — and full-coverage prices for Maine, Massachusetts, Michigan, Montana, North Dakota, Nebraska, New Hampshire, New Jersey, and Vermont — represent one-year rolling medians.

5 states with the lowest car insurance rates as of October 2026

New Hampshire retains the top spot for the most affordable car insurance, with rates well below the national averages of $99 per month for liability and $187 per month for full coverage. All five states remain in the same positions as the previous month.

State
Average Quote: Full Coverage
Average Quote: Liability Only
Overall Average
New Hampshire$85$52$69
Wyoming$94$50$72
Alaska$97$59$78
Iowa$111$56$84
Idaho$107$64$85
Disclaimer: All rates displayed in the table are averages of Insurify price data through September 2026. Full-coverage rates represent two-year rolling medians for most states. Liability-only rates — and full-coverage prices for Maine, Massachusetts, Michigan, Montana, North Dakota, Nebraska, New Hampshire, New Jersey, and Vermont — represent one-year rolling medians.

Rate increases on the way?

While car insurance rates have held steady or even slightly decreased in the first half of 2026, that trend may not continue through the rest of the year, according to Insurify’s Mid-Year Car Insurance Report.

Insurify’s data scientists project that 32 states will see rate increases in the final months of 2026, led by Connecticut (4%), West Virginia (3%), and Delaware, Virginia, Washington, D.C., Kentucky, Nevada, Wyoming, and Illinois each with a 2% projected increase.

Some states already experienced rate increases in early 2026. Connecticut, for example, has seen a 10% increase in statewide car insurance rates already this year, and Kentucky has seen a 7% increase so far. For other states, like West Virginia, the forecasted rate increases are the latest projection for a turbulent insurance market.

But not all states faced rate increases in the final months of 2026. Insurify projects that car insurance rates in New Mexico will decrease by 3% by the end of the year, and that rates in Arkansas, Minnesota, and Colorado will all decrease by 2% by the end of the year.

Factors that affect car insurance rates

Car insurance rates can vary significantly among drivers based on many factors that insurers use to estimate risk. Some common rating factors include:

  • Driving history: Insurers consider whether a driver has a clean record or infractions such as speeding, driving under the influence (DUI), or causing an accident.

  • Age: Driving experience and accident risk closely correlate with age, actuarial data shows.

  • Gender: Statistically, women are less likely than men to cause accidents and engage in risky behaviors like aggressive driving.

  • Location: Where a policyholder lives and drives affects their exposure to risk factors such as extreme weather, vehicle crime rates, and accident rates.

  • Credit history: Data indicates that drivers with better credit are less likely to file car insurance claims than those with poor credit.

  • Vehicle make and model: Vehicles that are less expensive or have multiple safety features cost less to insure.

  • Vehicle usage: Driving fewer miles per year reduces a vehicle’s exposure to the day-to-day risks of driving.

  • Vehicle equipment: Safety features like lane-keeping assist and blind-spot warning can help reduce the risk of accidents.

  • Coverage type: Generally, liability-only coverage costs less than full-coverage car insurance.

  • Coverage limits: The amount of coverage you buy affects annual premiums. Minimum coverage is typically the cheapest, but it doesn’t offer enough financial protection for most drivers.

  • Deductible: A higher collision and comprehensive coverage deductible (liability coverage has no deductible) reduces rates, as the insurer assumes less risk for the cost of repairs.

How to save on car insurance

Every state except New Hampshire requires drivers to carry a minimum amount of liability coverage. Insurance professionals recommend buying more coverage to provide greater financial protection in the event of an at-fault accident. And if a driver leases or finances a vehicle, the leasing company or lender will require them to buy full-coverage car insurance.

Drivers can take the following steps to reduce the cost of car insurance:

  • Drive safely. Avoid speeding, hard braking, distracted driving, and other risky driving behaviors that could cause a claim.

  • Look for discounts. Most insurers offer discounts, such as good student or multi-car discounts, that can help reduce premiums.

  • Increase the deductible. A higher collision and comprehensive deductible typically leads to lower rates.

  • Adjust coverages. Liability-only coverage is the cheapest insurance available, and minimum coverage is the cheapest liability option. But drivers should be careful and buy enough coverage to adequately protect themselves financially.

  • Comparison shop. Drivers should compare rates from multiple companies every time their policy comes up for renewal.

Methodology

Insurify data scientists analyzed more than 250 million rates from car insurance applications in Insurify’s proprietary database to calculate the premium averages displayed on this page. These premiums are real quotes that come directly from Insurify’s 50+ partner insurance companies in all 50 states and Washington, D.C. All premium averages reflect the cost of car insurance for drivers between the ages of 20 and 70 with clean driving records and average or better credit.

For most states, full-coverage premium prices represent two-year rolling medians to manage extreme market volatility seen over the past few years as insurance companies have sought substantial rate-increase approvals and deprioritized writing new policies amid rapidly rising costs.

Liability-only premium prices — as well as full-coverage prices in Maine, Massachusetts, Michigan, Montana, North Dakota, Nebraska, New Hampshire, New Jersey, and Vermont — represent one-year rolling medians.

Liability-only premium averages correspond to policies with the following coverage limits:

  • Bodily injury limits between state-minimum rates and $50,000 per person, $100,000 per accident

  • Property damage limits between $10,000 and $50,000

  • No additional coverage

Full-coverage premium averages correspond to the same bodily injury and property damage limits in addition to:

  • Comprehensive coverage with a $1,000 deductible

  • Collision coverage with a $1,000 deductible

For full-coverage historical data, please visit Insurify’s Auto Insurance Data Center. Data housed there dates back to 2021 and represents the average yearly cost of full coverage for drivers between the ages of 20 and 70 with a clean driving record and average or better credit.

Doug Bailey
Writer: Doug BaileySenior Content Writer

Qualifications:
  • 15 years at the Boston Globe

  • 5+ years covering insurance industry


Doug joined Insurify as a senior content writer in 2025. He was previously a regular contributor to InsuranceNewsNet.

Evelyn Pimplaskar
Editor: Evelyn PimplaskarEditor-in-Chief, Director of Content

Qualifications:
  • 10+ years in insurance and personal finance content

  • 30+ years in media, PR, and content creation


Evelyn leads Insurify’s content team. She’s passionate about creating empowering content to help people transform their financial lives and make sound insurance-buying decisions.

MacKenzie Korris
Reviewer: MacKenzie KorrisLicensed P&C Agent, Senior Insurance Copy Editor

Qualifications:
  • Licensed property and casualty insurance agent

  • 10+ years editing experience

  • NPN: 21630969


MacKenzie Korris is an insurance copy editor with a producer’s license for property and casualty insurance in Missouri.