Pet Insurance Rates Can Soar at Renewal, but Switching Insurers May Be Difficult

Rates are spiking across the country, and there are many reasons why.

Doug Bailey
Writer: Doug BaileySenior Content Writer

Qualifications:
  • 15 years at the Boston Globe

  • 5+ years covering insurance industry


Doug joined Insurify as a senior content writer in 2025. He was previously a regular contributor to InsuranceNewsNet.

Chris Schafer
Editor: Chris SchaferDeputy Managing Editor, News and Marketing Content

Qualifications:
  • 15+ years in content creation

  • 7+ years in business and financial services content


Chris is a seasoned writer/editor with past experience across myriad industries, including insurance, SAS, finance, Medicare, logistics, marketing/advertising, and many more.

Photo of an Insurify author
Reviewer: John LeachLicensed P&C Agent, Chief Copy Editor

Qualifications:
  • Licensed property and casualty insurance agent

  • 10+ years editing experience

  • NPN: 20461358


John is Insurify’s Chief Copy Editor, helping ensure the accuracy and readability of Insurify’s content. He’s a licensed agent specializing in home and car insurance topics.

Published | Reading time: 4 minutes

Why you can trust Insurify: Comparing accurate insurance quotes should never put you at risk of spam. We earn an agent commission only if you buy a policy based on our quotes. Our editorial team follows a rigorous set of editorial standards and operates independently from our insurance partners. Learn more.

Pet owners across the nation are getting a costly surprise a year into their pet insurance plans. The affordable coverage they initially bought gives way to soaring premiums at renewal.

The increases can be eye-popping, with some social media users reporting their pet insurance premiums jumped from $200 per year to $1,362 — a 581% increase.

Pet insurers and insurance professionals say rising veterinary costs, pet age, breed, location, and the claims experience of broader groups of animals can all affect premiums.

And there’s another wrinkle for consumers facing a big increase: Shopping around for coverage may not be as simple as it is with other insurance types.

The allure of low introductory prices for pet insurance

Some companies price aggressively to attract new business, Rami Sneineh, vice president and licensed insurance producer at Insurance Navy Brokers, told Insurify.

“To win new business, some insurance companies price policies low in the first year,” he said. “The actual cost of covering that pet is rarely reflected in that first-year premium.”

Nick VinZant, director of public relations at Trupanion, agreed. “Some pet insurance companies offer low introductory rates and then sharply raise premiums when you file a claim or as your pet ages,” he said.

Insurers wary of pre-existing conditions

For owners of pets with pre-existing conditions, securing new coverage can be difficult, bordering on impossible. Many insurers won’t cover a chronic or recurring condition the pet developed before the policy took effect.

Owners face an unpleasant choice — pay the higher renewal premium their current insurer offers or switch companies, potentially losing coverage for an expensive medical condition.

This difficult decision comes at a time when pet insurance premiums have climbed substantially in recent years, particularly for dogs.

The average annual U.S. premium for accident-and-illness coverage for a dog increased by about 22%, from $613 in 2020 to $749 in 2024, according to the North American Pet Health Insurance Association (NAPHIA). Just over half of that increase occurred in 2024, when the average dog premium jumped from $675 to $749.

Cat insurance rates have increased more slowly. The average accident-and-illness premium for cats rose from $367 in 2020 to $386 in 2024, about a 5% increase.

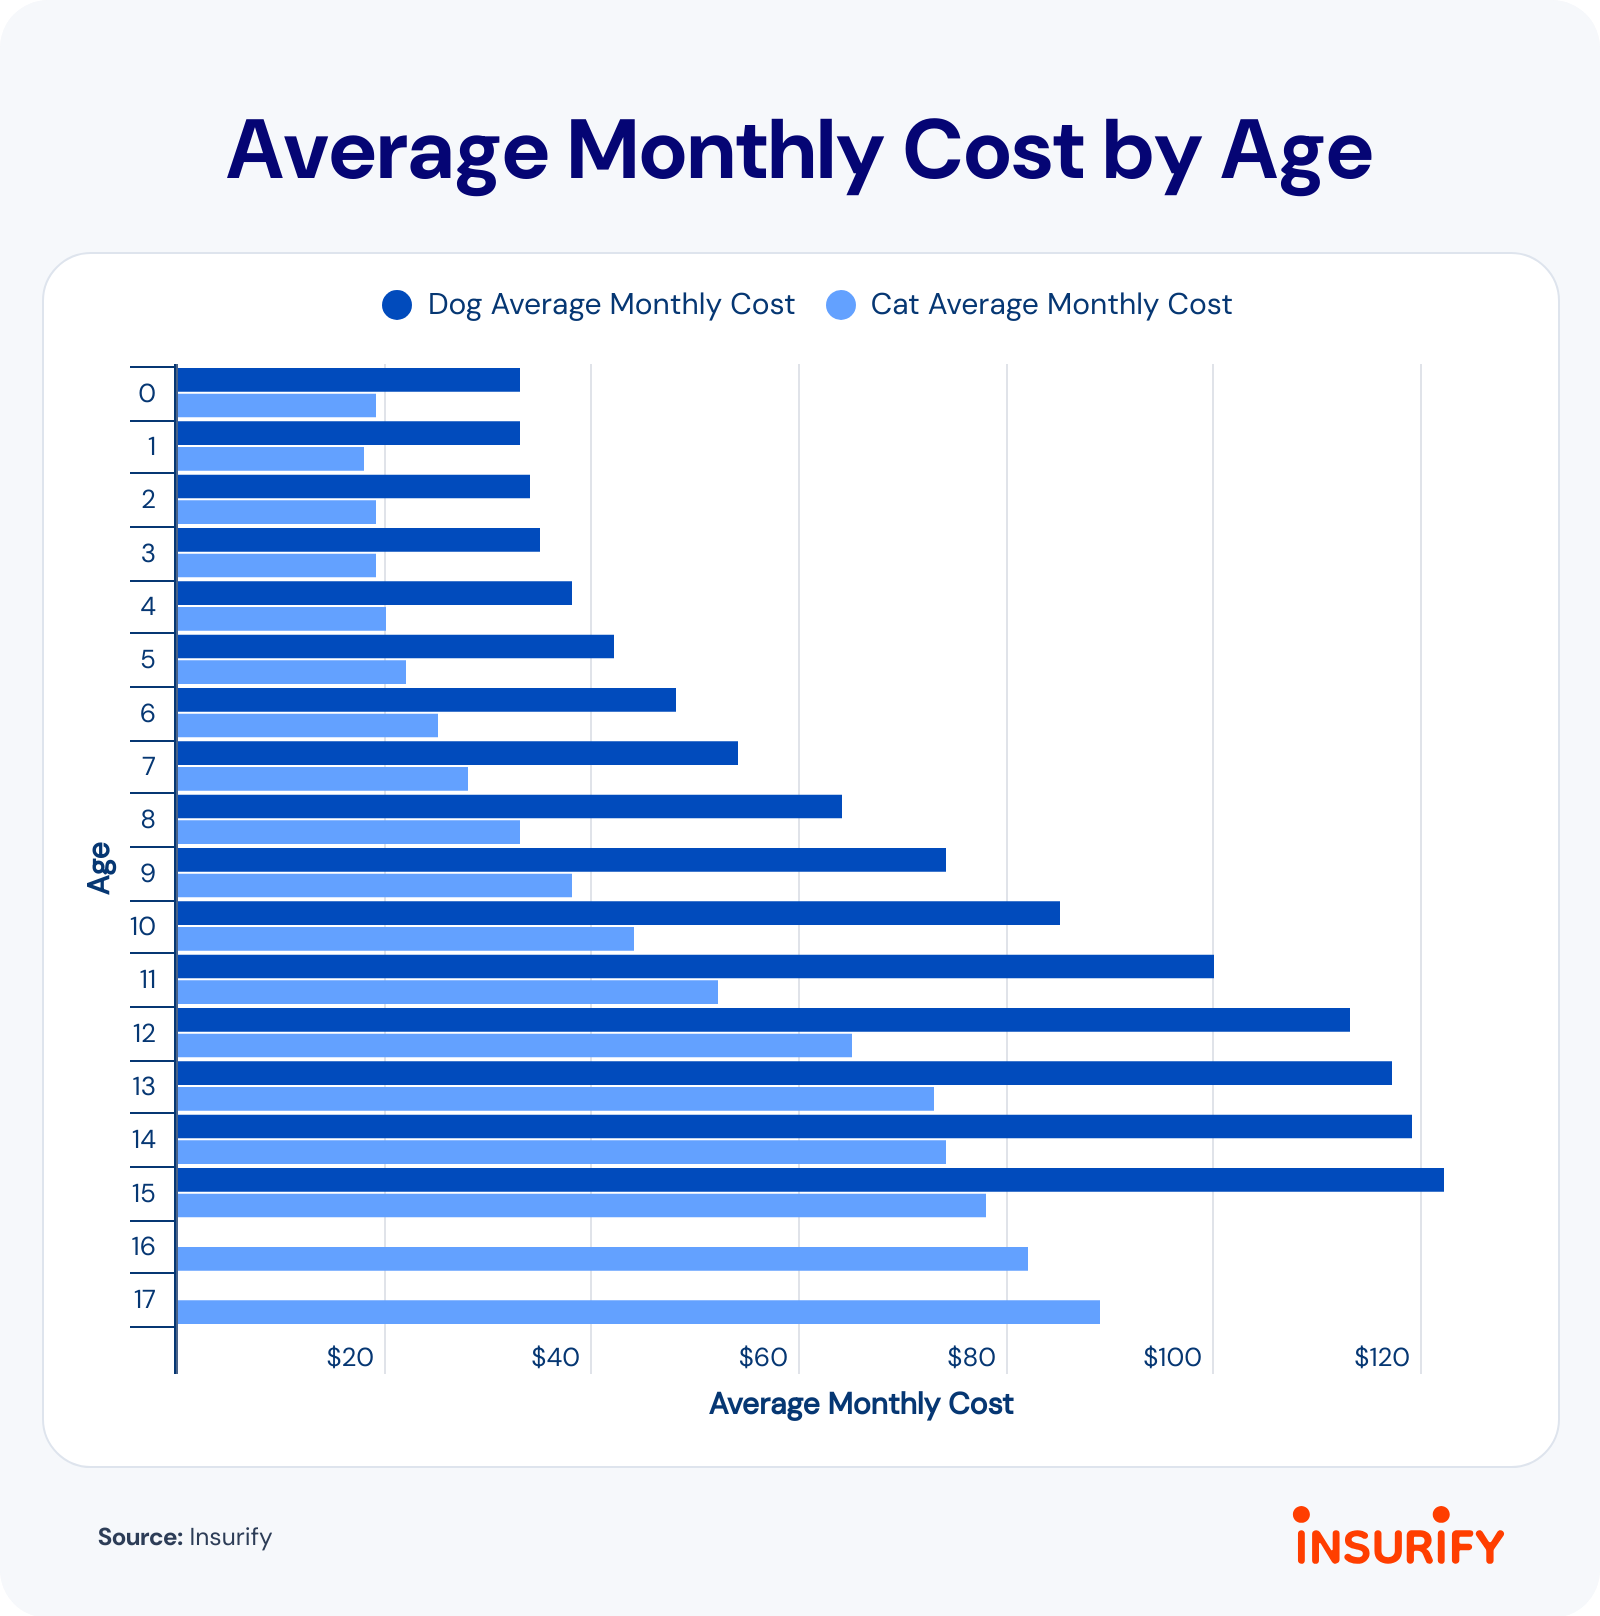
Insurify initial-quote data also shows that otherwise similar older pets can cost substantially more to insure than younger animals. A 10-year-old dog, for example, may cost three times as much to insure as a 1-year-old canine, per Insurify data listed below.

Pet insurance premiums are growing and so is the business

More than one-third of U.S. employers — 36% — now offer voluntary pet insurance, according to Gallagher’s 2026 U.S. Benefits Benchmarks Report, which surveyed 3,717 organizations. That’s up 13 percentage points from 23% in 2023. And nearly 75% of U.S. households own at least one pet, according to the American Pet Products Association.

As the number of pet owners climbs, the number of insured animals does as well.

About 7.6 million pets were insured in North America at the end of 2025, according to the NAPHIA. That figure is up 8.5% from 7.03 million a year earlier.

Altogether, the pet insurance industry collected about $6.2 billion in gross written premiums, a 19% increase from 2024.

Rising vet bills are showing up in insurance premiums

One major factor behind pet insurance pricing is the rising cost of veterinary care. Veterinary services inflation continues to substantially outpace the baseline national consumer price index (CPI), according to data from the U.S. Bureau of Labor Statistics. Prices rose 4.7% to 5.6% year over year and approximately 51% cumulatively over the last five to six years.

“The cost of veterinary care has increased significantly, and this is reflected in renewal costs,” said Sneineh.

“Better diagnostics, more specialty care, and the same kind of rising medical costs you’ve seen in human healthcare are all pushing vet bills up,” Sunil Manjunath, co-founder of One Touch Finance, told Insurify. “When an MRI or a cancer treatment costs more, your premium follows.”

Fetch Pet Insurance also pointed to veterinary inflation and increasingly sophisticated treatment as factors affecting premiums.

“Pet insurance is a regulated product, so premiums aren’t changed arbitrarily,” Julie Galante, chief insurance officer at Fetch Pet Insurance, told Insurify.

Rates are filed with state regulators and can change at renewal because of “rising veterinary costs, a pet’s age, and the growing use of advanced treatments as families increasingly pursue more sophisticated care for their pets,” Galante said.

Pet age affects premiums, but not always in the same way

Pet insurance premiums can depend on numerous factors, including species, breed, age, location, coverage level, and deductible.

But not all insurers treat age the same way.

“Insurance companies weigh that risk the same way they’d weigh a driver’s age in an auto policy, and older pets tend to generate more claims,” Sneineh said.

Fetch includes a pet’s age among the factors that can affect renewal premiums, Galante said.

Trupanion uses a different approach. The company considers a pet’s age at first enrollment but doesn’t raise its premium simply because the animal gets older, the company said.

Shopping around can help, but switching carries risks

Pet owners facing higher premiums don’t necessarily have to accept the renewal price without question. But consumers should investigate what they’ll lose as well as what they’ll save before changing insurers.

To save on pet insurance, experts recommend pet owners:

  • Buy coverage while a pet is young and healthy. Younger animals often cost less to insure, and enrolling before medical problems arise can reduce the number of conditions that are excluded as pre-existing.

  • Compare more than the initial premium. Ask insurers how age affects future pricing and whether an individual pet’s claims can affect renewal premiums.

  • Ask how the insurer determines renewal rates. Different insurers use different rating approaches. Ask specifically about age, location, veterinary inflation, individual claims, and the claims experience of broader groups of pets.

  • Ask whether new-customer pricing differs from renewal pricing. A low initial quote is less useful if the insurer’s pricing structure changes substantially after enrollment.

  • Consider changing coverage before changing insurers. Ask whether increasing the deductible or changing reimbursement and coverage levels could reduce the premium while preserving existing coverage.

  • Check pre-existing-condition rules before switching. Don’t cancel an existing policy until you know how the new insurer will treat conditions already in the pet’s medical record.

Doug Bailey
Writer: Doug BaileySenior Content Writer

Qualifications:
  • 15 years at the Boston Globe

  • 5+ years covering insurance industry


Doug joined Insurify as a senior content writer in 2025. He was previously a regular contributor to InsuranceNewsNet.

Chris Schafer
Editor: Chris SchaferDeputy Managing Editor, News and Marketing Content

Qualifications:
  • 15+ years in content creation

  • 7+ years in business and financial services content


Chris is a seasoned writer/editor with past experience across myriad industries, including insurance, SAS, finance, Medicare, logistics, marketing/advertising, and many more.

Photo of an Insurify author
Reviewer: John LeachLicensed P&C Agent, Chief Copy Editor

Qualifications:
  • Licensed property and casualty insurance agent

  • 10+ years editing experience

  • NPN: 20461358


John is Insurify’s Chief Copy Editor, helping ensure the accuracy and readability of Insurify’s content. He’s a licensed agent specializing in home and car insurance topics.