Home insurance affordability and cost transparency have become top issues in many states, especially as the U.S. approaches the midterm elections. Almost 1,900 counties saw their home insurance costs increase in the first half of the year, with more than 130 seeing double-digit increases, according to Insurify data.
Home insurance costs rose 12% in 2025, and the trend continued this year, with a 2.2% increase in the first half of 2026. Prices are on track to reach Insurify’s projected 4% rate increase by the end of the year. The national average cost of home insurance is $3,012 per year, according to Insurify data, but localized risk has made averages less helpful for understanding the true cost of protection for many homeowners.
Regulatory changes and inflation undeniably influence claims costs and insurer losses, but the primary culprit is clear: Severe weather risk is driving up home insurance premiums. Metro areas all along the Gulf Coast and throughout the Southeast are buyer’s markets, according to Zillow’s Market Heat Index.[1] But many home shoppers must weigh whether taking advantage of a buyer’s market is worth it if the property is too costly to insure.
Home insurance data shows another pattern, too. Wildfires and hurricanes remain major risk factors, but severe thunderstorms, which include hailstorms, tornadoes, lightning, and damaging winds, are increasingly responsible for skyrocketing insurance risk. As insurers gather more information and work to align insurance rates with regional risk, homeowners in high-risk areas are seeing their coverage costs climb.
Key findings
Five Minnesota counties saw average home insurance rates increase by 20% or more, according to Insurify data. The risk of severe hail and wind damage is largely driving higher costs in the state.
The five states with the largest percent increases in the average cost of home insurance are Minnesota (+$457), Louisiana (+$434), South Carolina (+$172), California (+$123), and Texas (+$180).
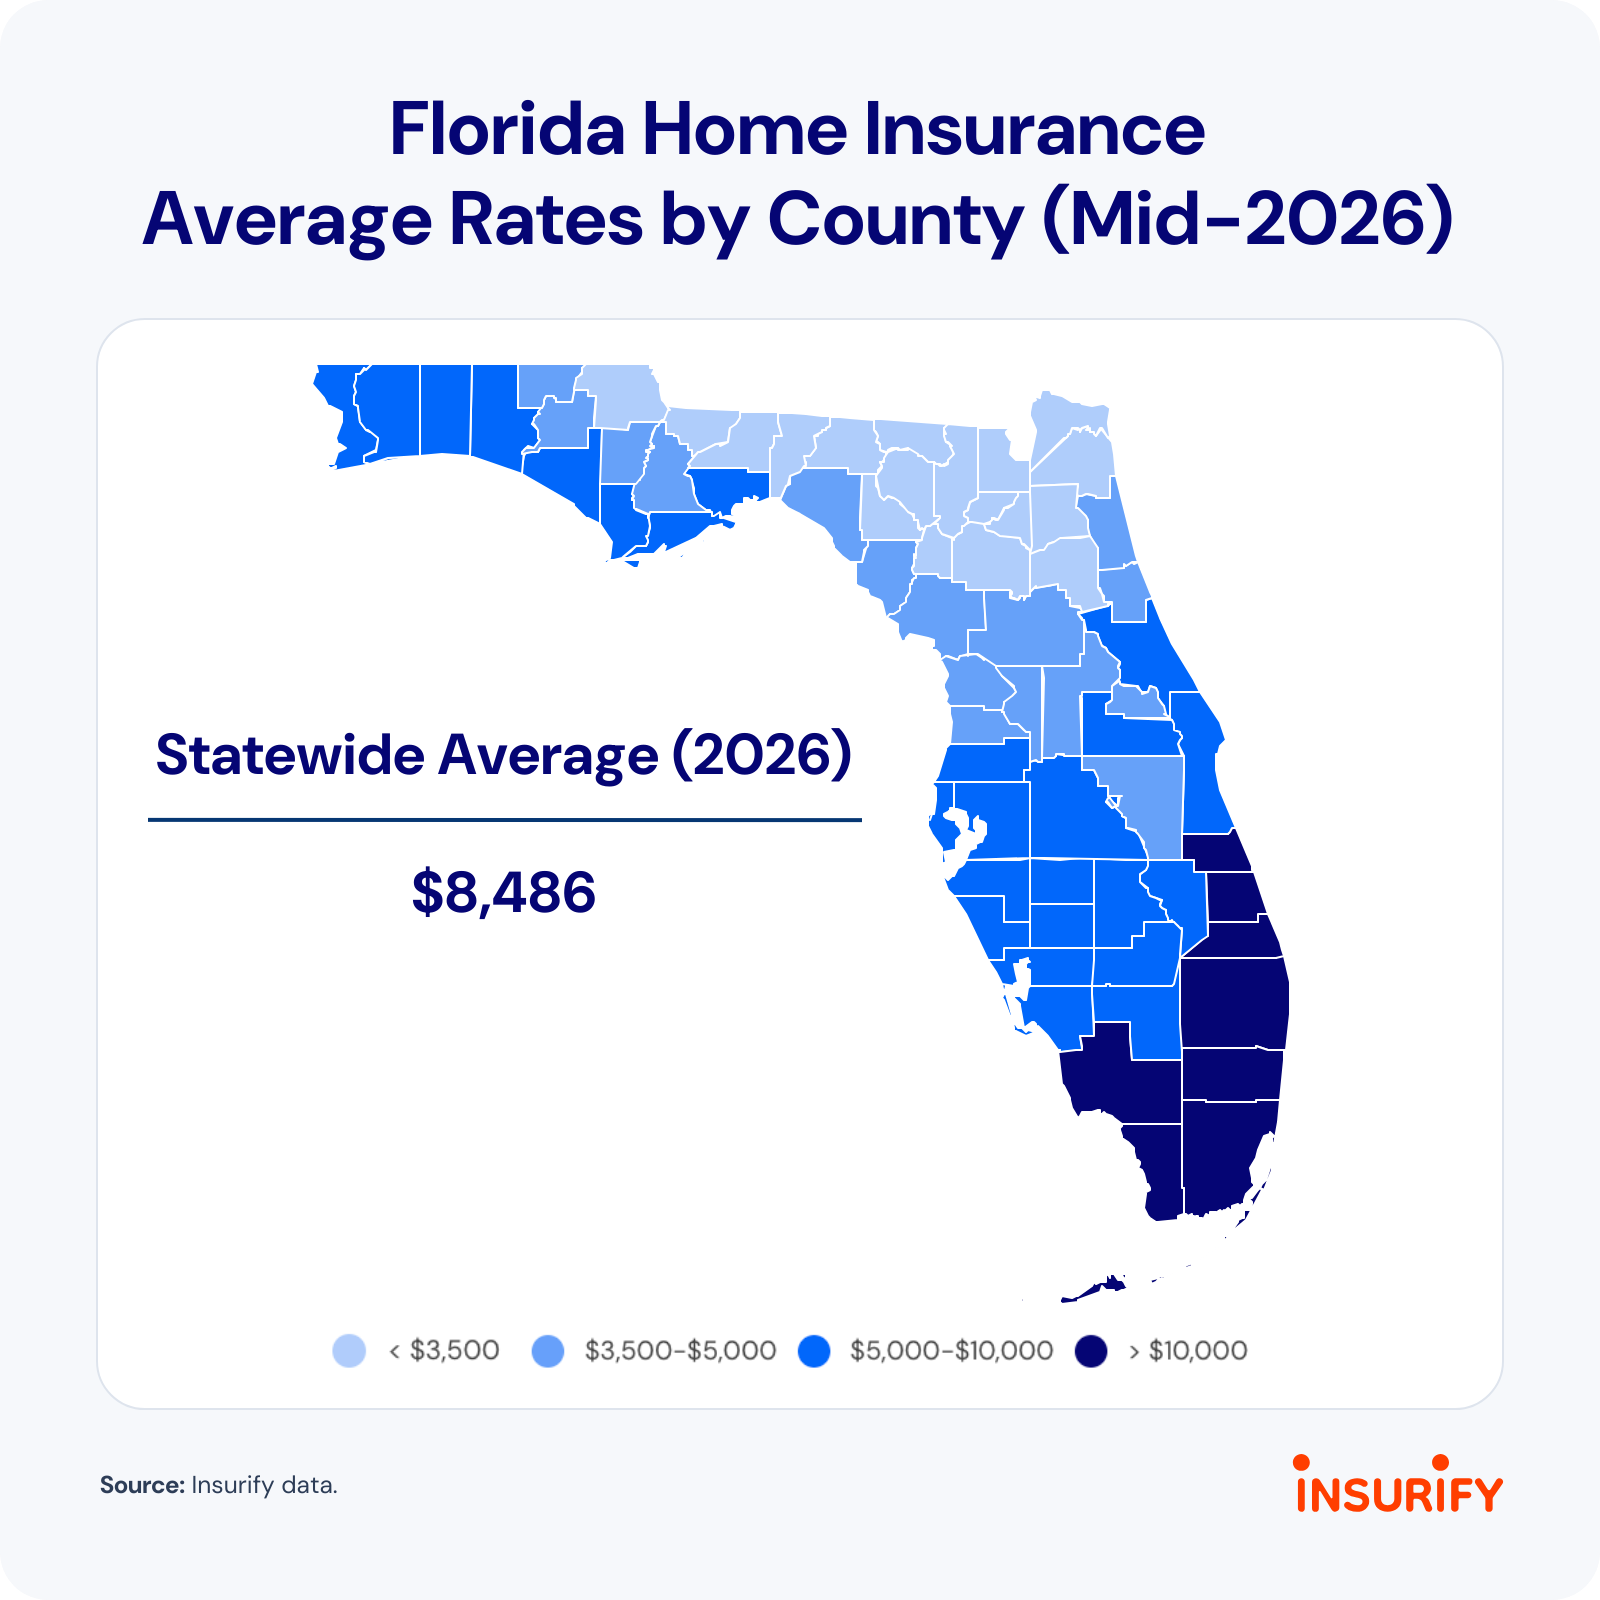
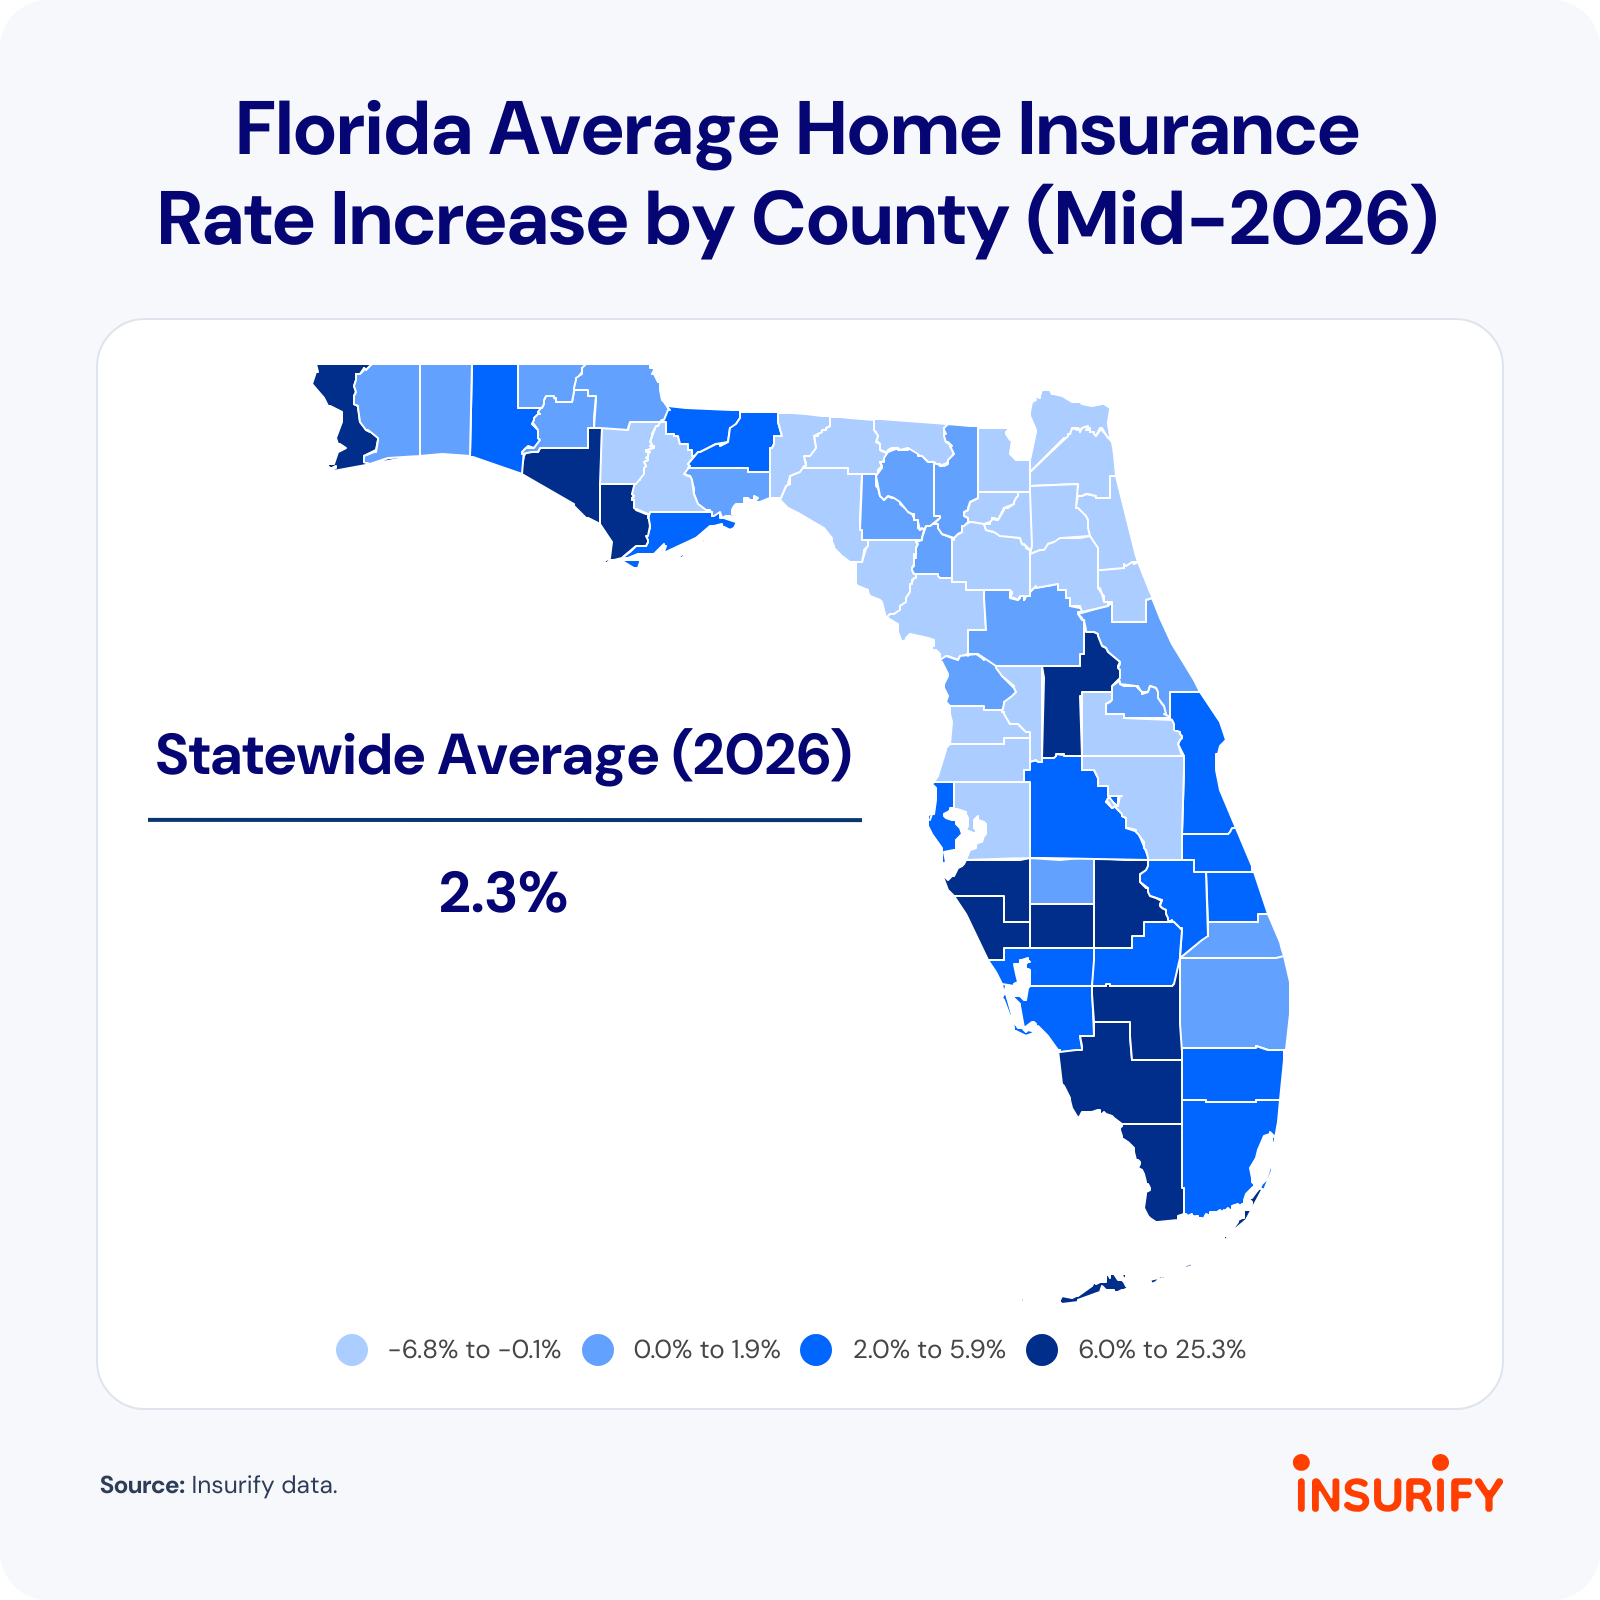
Florida, the most expensive state for home insurance at an annual average of $8,486, saw average home insurance rates increase by a modest 2.3% (+$194) in the first half of 2026, according to Insurify data.
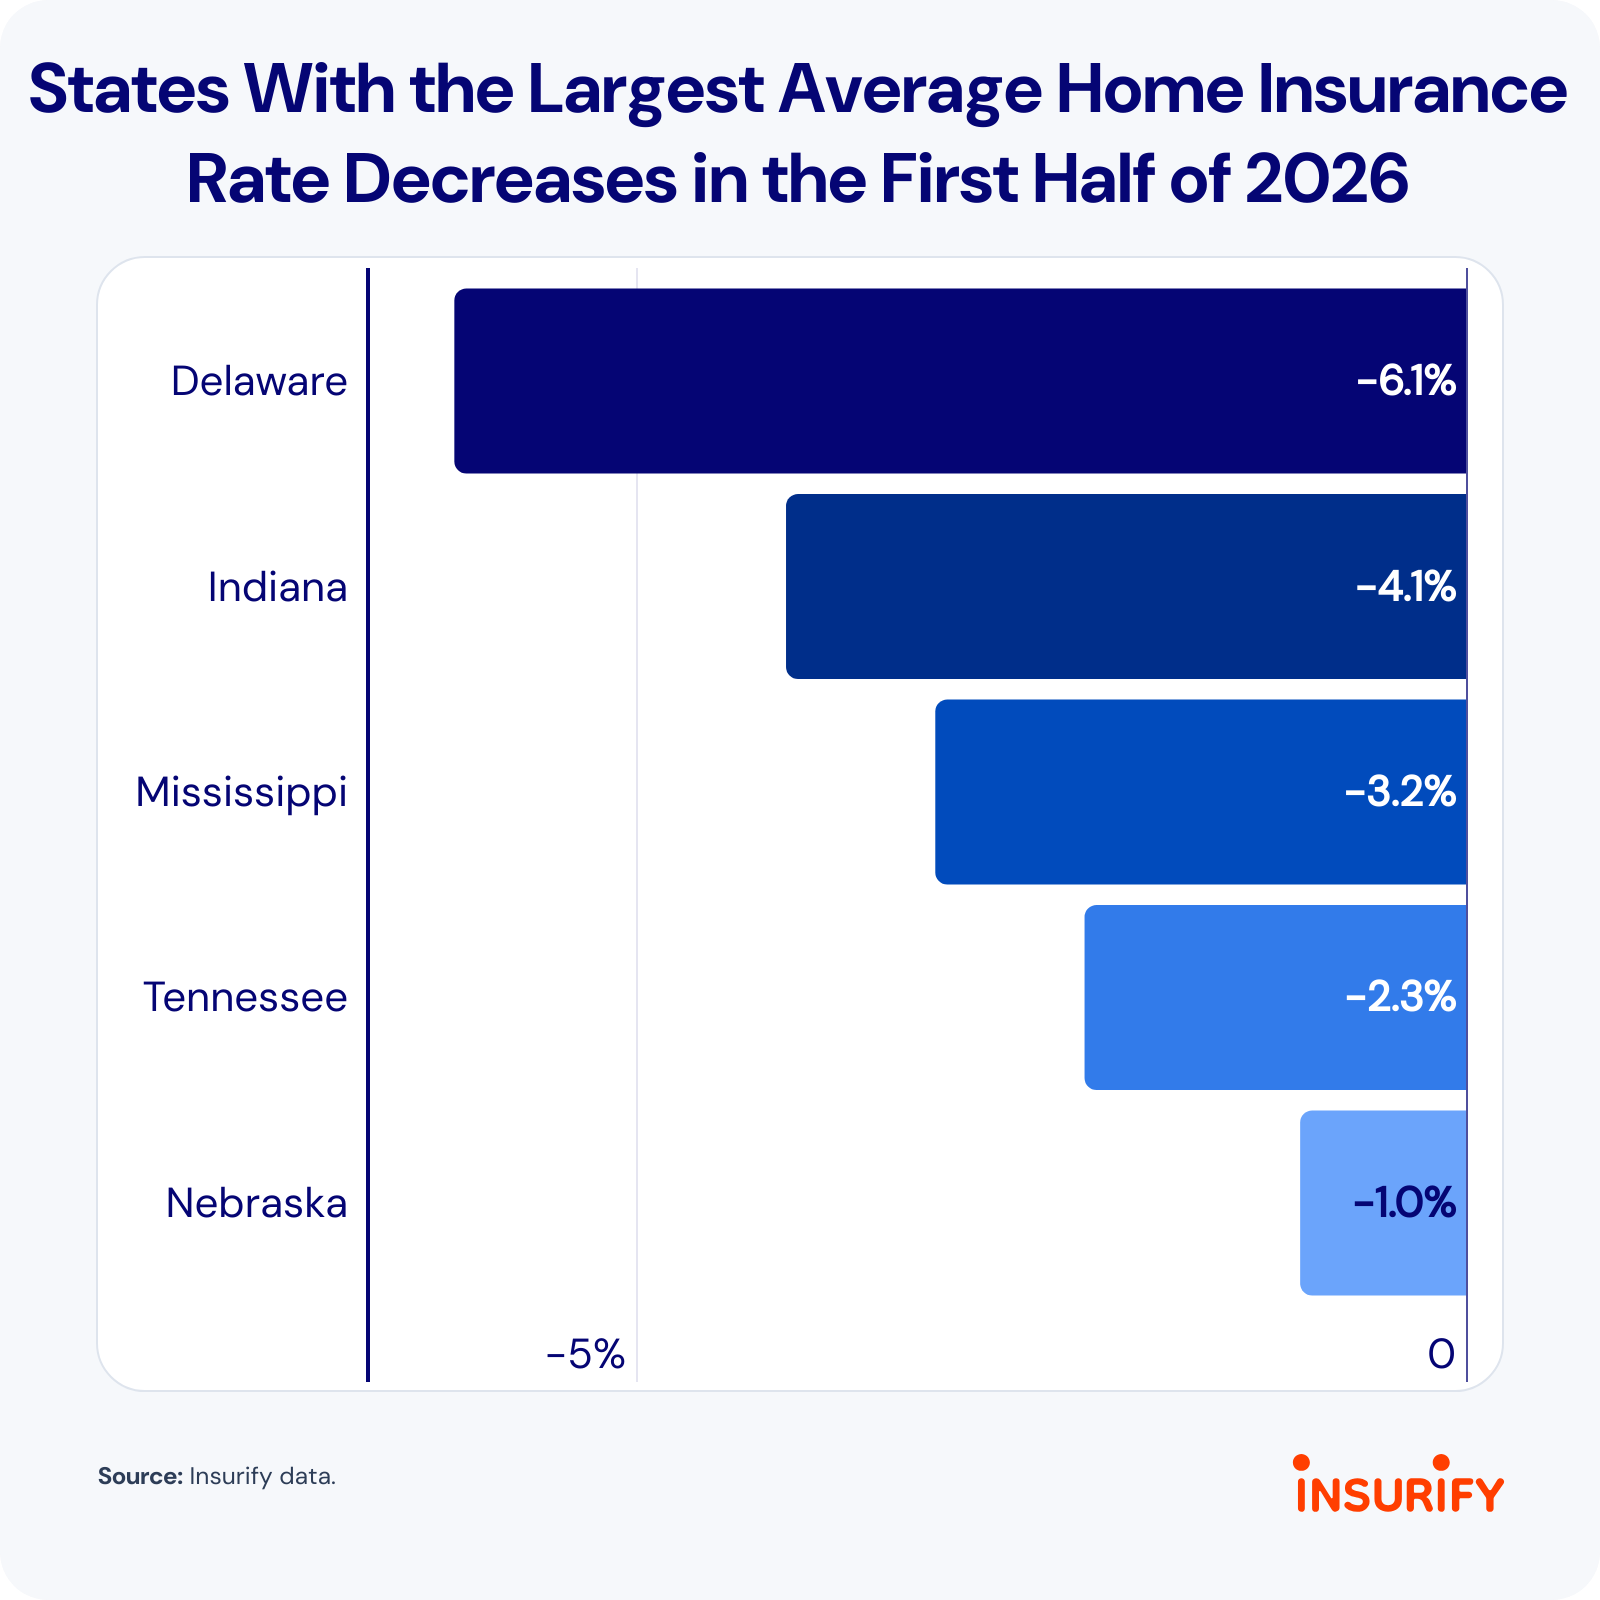
Some states saw average home insurance costs go down so far this year: Delaware (-$91) and Indiana (-$83) had the largest drops, according to Insurify data.
The 10 counties with the biggest home insurance rate increases so far in 2026
Counties along the Gulf Coast, Colorado’s eastern border, and Minnesota’s southern region make up the top 10 counties with the largest home insurance rate increases in the first half of 2026, according to Insurify data. Hurricane, wildfire, and severe storm risk, along with select regulatory and legislative changes, are major contributing factors to rising premiums.
Minnesota counties, in particular, dominate the list. From 2018 to 2024, policy non-renewals increased by 125% in the Midwest, according to the National Association of Insurance Commissioners (NAIC).[4] When non-renewals increase, average rates often rise as well, as higher-risk homeowners seek new coverage, sometimes with last-resort insurers at much higher rates. Across these areas, home insurance may be becoming a new and costly line item on many homeowners’ budgets.
Change in Home Insurance Premiums by County
1. Jefferson Parish, Louisiana
Change in home insurance premiums (first half of 2026): +33.0% (+$2,135)
Average annual home insurance premium mid-2026: $8,615
Typical state dwelling coverage amount: $298,283
Hurricanes Laura in 2020 and Ida in 2021 led to major insured losses. Louisiana insurers paid out $2.49 in 2020 and $4.07 in 2021 for every $1 they earned in premiums, according to the NAIC. And, when Ida made landfall, it hit Jefferson Parish the hardest.
The coastal parish, which includes parts of New Orleans, incurred $2.2 billion in insured losses, according to the Louisiana Department of Insurance (LDI).[5] Home insurers increased premiums as a result, making Jefferson Parish the fifth most expensive parish in the state, according to Insurify data. Its 33% premium increase in the first half of 2026 likely reflects insurers’ continued efforts to adjust premiums to reflect expected claims.
In 2025, Jefferson Parish experienced a historic January snowstorm and several severe wind events in the spring and summer, according to the National Centers for Environmental Information (NCEI). The storm caused direct and indirect damage, from frozen pipes to at least one space heater-related fire, which can lead to costly insurance claims.
2. Collier County, Florida
Change in home insurance premiums (first half of 2026): +25.3% (+$2,028)
Average annual home insurance premium mid-2026: $10,052
Typical state dwelling coverage amount: $328,842
Florida’s continued storm risk and effort to move customers from the state-backed Citizens Property Insurance Corporation to private insurers likely contribute to the state’s rising home insurance premiums.
Though 2025 didn’t bring a major severe weather event, hurricanes Ian in 2022 and Milton, Helene, and Debby in 2024 caused significant damage in Collier County. It had the fourth-highest number of reported claims following Hurricane Ian, and the Naples area experienced more than $550 million in property damage from severe weather events in 2024.
The state has been successfully moving policies from Citizens to the private home insurance market, and active Citizens policies continue to drop to record lows. But homeowners who receive a coverage offer that exceeds their Citizens premium by 20% or less are no longer eligible for a Citizens policy.[6] Collier County alone has seen a 24.9% drop in Citizens’ active policies since January, so it’s likely many homeowners have new policies with higher premiums.[7]
3. Le Sueur County, Minnesota
Change in home insurance premiums (first half of 2026): +23.9% (+$715)
Average annual home insurance premium mid-2026: $3,703
Typical state dwelling coverage amount: $407,360
Le Sueur County’s rising home insurance premiums likely reflect both escalating wind and hail risk and Minnesota’s regulatory response to those risks. Minnesota saw high insured losses in 2022 and 2023. In 2022, Minnesota home insurers paid out $1.58 for every $1 they made in premiums, according to the NAIC. The losses were largely due to a series of severe thunderstorms in May, which caused $90,000 in property damage in Le Sueur County alone, according to the NCEI.
But, since the start of 2024, Le Sueur County has had eight reports of severe hail, including July 2025 storms with hail 2 inches in diameter, and seven reports of severe winds, according to the NCEI.
In 2024, Minnesota legislators passed a law permitting insurers to non-renew policies if three or more covered lightning, wind, rain, or hail losses caused damage over $10,000 each.[8] This can lead directly to higher premium costs for homeowners if they need to obtain coverage from another insurer or the state-backed Minnesota FAIR Plan.
4. Watonwan County, Minnesota
Change in home insurance premiums (first half of 2026): +22.6% (+$681)
Average annual home insurance premium mid-2026: $3,697
Typical state dwelling coverage amount: $407,360
Climate risk and policy changes are also likely contributing to rising premiums in Watonwan County. The county has logged 12 severe hail events and five severe wind events since the beginning of 2024, according to the NCEI. And in May 2022, the same series of thunderstorms that hit Le Sueur County caused $100,000 in property damage in Watonwan County alone, demonstrating the region’s historic risk.
In 2024, the Minnesota Department of Commerce reported that homeowners insurance complaints had nearly doubled since 2020, mostly due to homeowners facing high out-of-pocket costs after wind and hail damage.[9] The department noted that insurers may have exclusions that narrow coverage or higher deductibles for wind and hail claims, contributing to those higher costs.
Minnesota’s rating system generally lets insurers begin using rates as soon as they file them and before regulators complete their review. Minnesota homeowners may feel the effects of climate risk in their premiums faster than in states with systems that require regulatory approval before insurers can implement rate changes.
5. Kit Carson County, Colorado
Change in home insurance premiums (first half of 2026): +22.0% (+$1,032)
Average annual home insurance premium mid-2026: $5,732
Typical state dwelling coverage amount: $324,724
Severe thunderstorms are contributing to rising home insurance premiums in several Colorado counties. Kit Carson County is squarely in Colorado’s Eastern Plains along the Kansas border, a region that sees the most hail and severe wind activity. Since the beginning of 2024, the county has had 48 reports of severe hail and 83 reports of severe winds, according to the NCEI.
Though Kit Carson County didn’t experience much wildfire activity from 2020 through 2025, a devastating wildfire caused $20 million in property damage in April 2026, according to the NCEI. This may already be showing up in premiums as homeowners renew their policies, with insurers adjusting rates to reflect increased risk.
6. Martin County, Minnesota
Change in home insurance premiums (first half of 2026): +21.9% (+$655)
Average annual home insurance premium mid-2026: $3,643
Typical state dwelling coverage amount: $407,360
Martin County lies just south of Watonwan County in southern Minnesota, so the two face similar risks. Since 2024, Martin County has had just four severe hail events, fewer than Watonwan, and 13 severe wind events, according to the NCEI.
A 2024 state amendment may affect premiums in less populated areas. Minnesota changed a law prohibiting insurers from charging different premiums across ZIP-code areas within the same city or town with fewer than 60,000 residents. This could raise premiums for some homeowners with higher severe-weather risk, since insurers can create smaller geographic areas to set prices and homeowners aren’t sharing those costs with lower-risk properties.
7. St. John the Baptist Parish, Louisiana
Change in home insurance premiums (first half of 2026): +21.5% (+$1,395)
Average annual home insurance premium mid-2026: $7,875
Typical state dwelling coverage amount: $298,283
St. John the Baptist Parish, just northwest of New Orleans, experienced wind and flood damage following Hurricane Francine in September 2024. Heavy rain caused significant flash flooding, blocking roads and damaging homes, according to a post-storm report.[10] Though home insurance doesn’t cover flood damage, costly wind claims and the indication of elevated storm risk can lead to higher premiums.
Climate risk is also affecting rates amid a shifting regulatory environment. Louisiana adopted a different rating system similar to Minnesota’s, so rate increases may reach homeowners faster. The state also changed a law that had protected long-standing homeowners policies from non-renewal.[11] If an insurer non-renews a relatively inexpensive policy and a homeowner must then purchase a new, higher-priced policy, it could show up in rate data as a major premium increase.
8. Hennepin County, Minnesota
Change in home insurance premiums (first half of 2026): +20.9% (+$784)
Average annual home insurance premium mid-2026: $4,545
Typical state dwelling coverage amount: $407,360
In 2022 and 2023, Minnesota had particularly bad years for insured losses, and Hennepin County saw some of the worst damage. Supercell thunderstorms produced damaging hail and wind in August 2023, causing $14 million in property damage just in Hennepin County, according to the NCEI. And, since 2024, Hennepin County has received 17 reports of severe hail and 54 reports of severe wind, according to the NCEI.
Home to Minneapolis, Hennepin County’s risk stems from its concentration of property and higher risk of costly insured losses. The estimate of how much damage disasters could cause each year is high, according to the Federal Emergency Management Agency’s (FEMA) Resilience Analysis and Planning Tool (RAPT). It has a high risk rating for hailstorms, tornadoes, strong winds, lightning, and inland flooding, according to RAPT.
9. Prowers County, Colorado
Change in home insurance premiums (first half of 2026): +20.8% (+$949)
Average annual home insurance premium mid-2026: $5,520
Typical state dwelling coverage amount: $324,724
Like Kit Carson County, Prowers County is also along the Kansas border in Colorado’s Eastern Plains. Prowers County has seen a lot less action, but it’s still facing an elevated severe thunderstorm risk. The county has had 26 reports of severe wind and 10 reports of severe hail since 2024, according to the NCEI.
A Colorado Department of Insurance analysis found that hail risk accounts for 26% to 54% of the total home insurance premium, depending on the county.[12] The data showed that even counties that don’t experience as much hail are still paying a high percentage of home insurance premiums on hail.
10. Steele County, Minnesota
Change in home insurance premiums (first half of 2026): +20.0% (+$629)
Average annual home insurance premium mid-2026: $3,773
Typical state dwelling coverage amount: $407,360
Steele County, just southeast of Le Sueur County, hasn’t experienced significant damage from severe weather events in the last few years. But it’s in that same southern Minnesota region seeing heightened hail and wind activity. Since the start of 2024, Steele County has had three reports of severe wind and nine of severe hail, including one in April 2026 for hail 3.5 inches in diameter, according to the NCEI.
But rising home insurance premiums can reflect both regional risk and hyperlocal risk. In 2022, State Farm, Minnesota’s largest insurer, reported paying $799 million in hail claims alone, the most of any state that year.[13] So, even without a major loss history in Steele County, insurers may be seeing the storm activity throughout southern Minnesota and pricing policies to account for that claims risk.
The states where home insurance rates changed the most in the first half of 2026
Severe thunderstorms, along with regulatory changes, have contributed to significant increases in home insurance rates in Minnesota and Louisiana, as many counties on the top 10 list demonstrate. Similar factors are also influencing premiums in South Carolina, California, Texas, and other states with the highest average increases in home insurance rates in 2026.
Change in Home Insurance Premiums by State
State | Change in Home Insurance Premiums (First Half of 2026) | Average Annual Home Insurance Premium (Mid-2026) | Typical Dwelling Coverage Amount |
|---|---|---|---|
| Alaska | -0.2% | $1,446 | $400,000 |
| Alabama | 0.3% | $3,939 | $329,117 |
| Arkansas | 0.4% | $3,142 | $311,941 |
| Arizona | 1.8% | $2,143 | $322,162 |
| California | 5.0% | $2,578 | $488,000 |
| Colorado | 3.5% | $4,137 | $324,724 |
| Connecticut | 0.1% | $2,207 | $404,025 |
| District of Columbia | 0.0% | $1,688 | $444,245 |
| Delaware | -6.1% | $1,403 | $383,520 |
| Florida | 2.3% | $8,486 | $328,842 |
| Georgia | 0.6% | $2,896 | $369,910 |
| Hawaii | 0.0% | $2,566 | $500,000 |
| Iowa | 0.9% | $2,828 | $349,230 |
| Idaho | 0.0% | $1,675 | $337,965 |
| Illinois | 1.0% | $3,414 | $416,267 |
| Indiana | -4.1% | $1,940 | $322,217 |
| Kansas | -0.3% | $3,301 | $292,166 |
| Kentucky | 1.7% | $2,820 | $306,411 |
| Louisiana | 8.6% | $5,484 | $298,283 |
| Massachusetts | -0.1% | $2,168 | $455,417 |
| Maryland | 1.1% | $2,209 | $372,773 |
| Maine | -0.1% | $1,372 | $340,916 |
| Michigan | 1.0% | $2,237 | $361,927 |
| Minnesota | 12.9% | $3,987 | $407,360 |
| Missouri | 0.5% | $2,840 | $341,009 |
| Mississippi | -3.2% | $3,624 | $320,702 |
| Montana | 2.3% | $2,454 | $340,515 |
| North Carolina | 0.0% | $3,345 | $356,474 |
| North Dakota | 1.7% | $2,464 | $296,348 |
| Nebraska | -1.0% | $3,987 | $337,800 |
| New Hampshire | 2.8% | $1,474 | $372,382 |
| New Jersey | 0.2% | $1,771 | $465,088 |
| New Mexico | 2.6% | $2,338 | $308,483 |
| Nevada | 1.5% | $1,698 | $391,571 |
| New York | 0.1% | $2,143 | $385,269 |
| Ohio | 3.1% | $1,653 | $320,653 |
| Oklahoma | -0.9% | $4,919 | $291,812 |
| Oregon | 0.3% | $1,489 | $395,182 |
| Pennsylvania | 3.5% | $1,739 | $401,219 |
| Rhode Island | 0.7% | $3,001 | $424,627 |
| South Carolina | 5.6% | $3,264 | $336,243 |
| South Dakota | -0.2% | $2,757 | $329,634 |
| Tennessee | -2.3% | $2,948 | $326,041 |
| Texas | 4.1% | $4,560 | $326,004 |
| 2.2% | $3,012 | $341,512 | |
| Utah | 1.4% | $1,338 | $316,899 |
| Virginia | 3.3% | $1,774 | $332,537 |
| Vermont | -0.7% | $1,080 | $367,949 |
| Washington | 3.5% | $1,587 | $387,899 |
| Wisconsin | 1.5% | $1,624 | $347,522 |
| West Virginia | 0.1% | $1,589 | $325,378 |
| Wyoming | 0.0% | $1,929 | $311,641 |
1. Minnesota
Change in home insurance premiums (first half of 2026): +12.9% (+$457)
Average annual home insurance premium mid-2026: $3,987
Typical state dwelling coverage amount: $407,360
Minnesota’s rising premiums are mostly due to the state’s increasing risk of damage from severe thunderstorms. Minnesota ranks highly for buildings and value with significant hail damage risk, according to Cotality’s 2026 Severe Convective Storm Risk Report.[14] Nearly 1.8 million homes and $899 billion of reconstruction cost value have a moderate or greater risk of hail damage, according to Cotality.
This year, severe weather caused $10.3 million in property damage in Minnesota from January through May, according to the NCEI. A tornado outbreak outside of Rochester caused $8.2 million of that damage, and hailstorms around the same time caused $1.1 million of damage.
2. Louisiana
Change in home insurance premiums (first half of 2026): +8.6% (+$434)
Average annual home insurance premium mid-2026: $5,484
Typical state dwelling coverage amount: $298,283
In 2025 and 2026, severe thunderstorms, not hurricanes, caused the most property damage in Louisiana, according to the NCEI. In July 2025, lightning struck a two-story apartment building in Baton Rouge, causing a fire and $1.8 million of damage.
The state’s transition to a different rating system may also be leading to faster premium increases. Louisiana deems rate change filings approved unless the commissioner acts to stop or change them within 30 days, allowing insurers to reflect losses in premiums more quickly.
3. South Carolina
Change in home insurance premiums (first half of 2026): +5.6% (+$172)
Average annual home insurance premium mid-2026: $3,264
Typical state dwelling coverage amount: $336,243
In 2024, severe thunderstorms, including several tornadoes, hailstorms, and thunderstorms, caused nearly $30 million in property damage in South Carolina, according to the NCEI. That led insurers to pay out more in claims than they earned in premiums, according to the NAIC.
Last year’s weather demonstrated an ongoing risk, when severe thunderstorms alone caused $967,000 in property damage, according to the NCEI. South Carolina’s average cost of home insurance increased by 20% from 2024 to 2025, so rising premiums likely demonstrate insurers’ efforts to charge more in areas where they expect higher losses.
4. California
Change in home insurance premiums (first half of 2026): +5.0% (+$123)
Average annual home insurance premium mid-2026: $2,578
Typical state dwelling coverage amount: $488,000
The Los Angeles County wildfires caused billions of dollars in insured losses in 2025. As of March 2026, insurers have paid out $23.7 billion in claims for those fires, according to the California Department of Insurance.[15] Actual insured losses could be much higher, though: Swiss Re estimated them at $40 billion.
California home insurers paid out $1.69 for every $1 they earned in 2025, according to the NAIC, so rising premiums show insurers trying to price policies based on changing risk. The state’s FAIR Plan recently announced a 29.1% rate hike for homeowners this fall.[16] Regulators also approved insurers’ use of forward-looking catastrophe models in rate filings, provided they insure more policies in at-risk areas, which could lead to higher rates.[17]
5. Texas
Change in home insurance premiums (first half of 2026): +4.1% (+$180)
Average annual home insurance premium mid-2026: $4,560
Typical state dwelling coverage amount: $326,004
More than 7.8 million Texas homes have a moderate or greater risk of hail damage, according to Cotality. That adds up to more than $3 trillion of reconstruction cost value. Hail drove more than $3 billion in insured losses for home insurers in 2025, according to the Texas Department of Insurance.[18]
Environmental scientists warn that hailstones are getting bigger, which can lead to more severe damage and costlier claims. So far in 2026, hail has caused $3.2 million in property damage, and thunderstorm wind has caused $4.2 million in property damage, according to the NCEI.
6. Washington
Change in home insurance premiums (first half of 2026): +3.5% (+$54)
Average annual home insurance premium mid-2026: $1,587
Typical state dwelling coverage amount: $387,899
Washington’s rising premiums may largely reflect the state’s increasing wildfire risk. In 2025, several wildfires in the late summer and early fall caused $543.5 million in property damage, according to the NCEI. So far in 2026, high winds and flooding have caused the most property damage.
Inflation affecting construction costs is also likely contributing to higher claims costs. So, as insurers adjust rates to reflect shifting climate risk, they’re also accounting for higher claim payouts.
7. Colorado
Change in home insurance premiums (first half of 2026): +3.5% (+$141)
Average annual home insurance premium mid-2026: $4,137
Typical state dwelling coverage amount: $324,724
Wildfires, in particular, have caused significant damage throughout Colorado in recent years. They caused $1.1 million in property damage in 2025, and a wildfire in April 2026 caused $20 million in damage, according to the NCEI. The state also has significant hail-damage exposure: 1.5 million homes and $741.6 billion in reconstruction cost value, according to Cotality. Rising premiums could indicate home insurers are charging more in areas where they anticipate costly claims.
8. Pennsylvania
Change in home insurance premiums (first half of 2026): +3.5% (+$58)
Average annual home insurance premium mid-2026: $1,739
Typical state dwelling coverage amount: $401,219
Changing climate risk has led to rising premiums for many Pennsylvania homeowners. Though the state’s average premium increased by 3.5%, some counties saw bigger rate spikes. Westmoreland County, just east of Pittsburgh, saw average home insurance rates increase by 12.7% (+$194) in the first half of 2026, according to Insurify data.
The same county experienced a hailstorm in 2022 that caused $1.2 million in property damage, according to the NCEI. Strong thunderstorm winds and a tornado caused $1.5 million in property damage in 2024.
9. Virginia
Change in home insurance premiums (first half of 2026): +3.3% (+$57)
Average annual home insurance premium mid-2026: $1,774
Typical state dwelling coverage amount: $332,537
Severe weather has caused $24.8 million in property damage throughout Virginia since the beginning of 2025, according to the NCEI. Coastal flooding and flash flooding from heavy rains have caused most of the damage, but severe wind events, lightning, and hail account for nearly a third of it.
The three eastern Virginia counties that saw the highest rate increases all have a history of property damage from severe thunderstorms. Chesapeake had the largest increase, at 15.4% (+$365) in the first half of 2026, bringing its annual average to $2,729, according to Insurify data.
10. Ohio
Change in home insurance premiums (first half of 2026): +3.1% (+$49)
Average annual home insurance premium mid-2026: $1,653
Typical state dwelling coverage amount: $320,653
Severe weather has caused $10.5 million in property damage in Ohio just since the start of 2025, according to the NCEI. Wind events, particularly thunderstorm winds and tornadoes, have caused the most damage, but hail is also contributing. Just one hailstorm in April 2026 caused $1 million in property damage, according to the NCEI. Defiance and Henry counties in northwestern Ohio saw the largest average annual rate increases, by $104 in the first half of 2026, according to Insurify data.
Delaware sees the largest average premium drop in 2026 so far
The premium decreases in Delaware could indicate some stabilization in the market. Average home insurance costs increased 8.7% in Delaware from 2023 to 2025, according to Insurify data, possibly a reaction in part to the damage from Hurricane Ida in 2021. But, while inflation continues to affect claims costs, Delaware hasn’t experienced major severe weather damage in the last few years, according to the NCEI. This could demonstrate a lower risk to insurers, leading to lower premiums.
)
What’s behind Florida’s stabilizing home insurance rates
Florida remains the most expensive state for home insurance, at an annual average of $8,486, according to Insurify data, largely due to its exceptionally high hurricane risk. And, in the first half of 2026, Florida has seen a modest 2.3% increase in the average cost of home insurance.
)
)
Florida regulators attribute the drop or stabilization in premiums to a series of legislative changes. These largely affect claims handling and litigation, such as eliminating one-way attorney fees. For example, even if a policyholder wins a lawsuit, they may still have to pay their own attorney’s fees, whereas previously the court would generally require the insurer to pay them.[19]
Evidence already suggests that these changes are reducing insurer costs: Insurers’ court defense costs fell from $992.89 per claim in 2022 to $817.64 in 2024, according to the Florida Office of Insurance Regulation.[20] And, for residential policies effective in 2024 or later, 39 insurers requested rate decreases and 100 insurers requested no rate change.
These changes indicate some market stabilization, but they also represent a trade-off. Home insurance policyholders have lost some of their ability to challenge insurers over claims because the changes have made litigation much more expensive.
Tips: How homeowners can save amid rising premiums
In regions with increasingly severe weather risk, home insurance is becoming a larger line item in the budget. But homeowners have several strategies to help reduce insurance costs. Some come with trade-offs, but others are simple, easy ways to save on coverage.
For example, increasing the policy’s deductible or reducing coverage limits can both lower premiums, but they also expose homeowners to greater financial risk. If they have to file a claim, homeowners must pay the higher deductible out of pocket before their coverage kicks in. So, before raising the deductible or adjusting coverage limits, homeowners should carefully consider what out-of-pocket costs they can manage and how much financial protection they really need.
Shopping around and comparing home insurance quotes is also one of the best strategies to save on coverage. Homeowners should get at least three quotes to ensure they secure the best deal for the coverage they need. It also pays to seek out every available discount. For example, bundling multiple policies with the same insurer can mean significant savings, and stacking discounts for things like setting up auto pay and paying the policy in full can add up.
Methodology
Insurify determined the average cost of home insurance based on its proprietary database and aggregated rate filings from Quadrant Information Services. Unless otherwise noted, average insurance rates in each state and county reflect the median cost of an HO-3 policy with that state’s average dwelling coverage limit, a liability limit equal to 75% of that dwelling limit, standard personal property and loss of use limits, a 5% wind/hurricane deductible, a 2% hail deductible, and a $1,000 deductible for all other claims. Costs assume homeowners with good credit and zero claims in the past five years living in a single-family frame house.
Sources
- Zillow. "Market Heat Index."
- Weather.gov. "Hail Threat Defined."
- Weather.gov. "Wind Threat Defined."
- National Association of Insurance Commissioners. "Examining Homeowner Property Insurance Market Dynamics."
- Louisiana Department of Insurance. "Hurricane Ida."
- Citizens Property Insurance Corporation. "Personal and Commercial Lines Depopulation Program Guide."
- Citizens Property Insurance Corporation. "Policies in Force."
- Minnesota Legislature. "Minnesota Session Laws - 2024 Regular Session."
- Minnesota Commerce Department. "Complaints to MN Department of Commerce about homeowner insurance doubled since 2020."
- Weather.gov. "Parish and County Impacts Associated with Hurricane Francine 2024."
- Louisiana State Legislature. "2024 Regular Session: House Bill No. 611."
- Colorado Division of Insurance. "Governor Polis and Division of Insurance: We Must Find Innovative Solutions to Save Colorado Homeowners Money on Insurance Costs."
- State Farm. "State Farm reports $1 BILLION increase in hail claim costs."
- Cotality. "2026 Severe Convective Storm Risk Report."
- California Department of Insurance. "LA County Wildfire Claims Tracker."
- KQED. "California FAIR Plan Announces 29.1% Rate Hike for Homeowners This Fall."
- California Department of Insurance. "Reform made real — California Department of Insurance completes final evaluation of innovative forward-looking model to address California’s coverage crisis."
- Texas Department of Insurance. "Texas homeowners insurance market overview."
- Florida State Senate. "An act relating to property insurance."
- Florida Office of Insurance Regulation. "PROPERTY INSURANCE STABILITY REPORT."
)
)
)
)
)
)